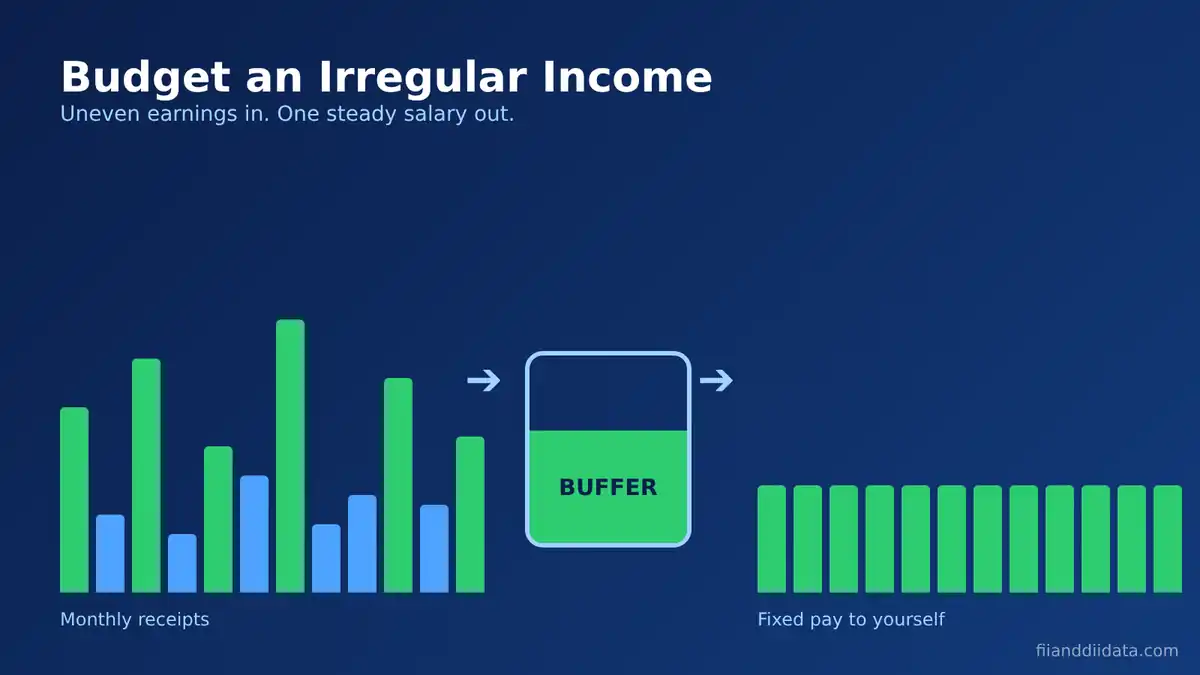
Learning how to budget an irregular income starts with one change: stop spending what you earn each month and start paying yourself a fixed salary from a separate holding account. Freelancers, consultants, gig workers and commission earners in India deal with this every month, and the group is growing. NITI Aayog estimated 77 lakh gig workers in 2020-21 and projected 2.35 crore by 2029-30 (report released 27 June 2022). This guide shows the full system with real numbers.
Key Takeaways
- Route every payment into one holding account and pay yourself the same amount each month.
- Set that fixed salary below your 12-month average take-home income, not at your best month.
- Keep a buffer of at least three months of salary before you increase spending.
- Set aside tax first; advance tax is due on 15 June, 15 September, 15 December and 15 March.
- Use strong months to refill the buffer and invest, and cut back to essentials in lean months.
Table of Contents
- Why Normal Budgets Fail With Variable Pay
- How to Budget an Irregular Income: The 5-Step System
- A Worked Example: 12 Months of Freelance Income
- Tax Planning When Your Income Is Irregular
- What to Do in Lean and Strong Months
- Saving and Investing With an Irregular Income
- Mistakes to Avoid When You Budget an Irregular Income
- Your Irregular Income Budget Checklist
- FAQ
- The Bottom Line
Why Normal Budgets Fail With Variable Pay
Most budgeting advice assumes a salary that lands on the same date every month. A salaried person can fix rent, EMIs and a SIP against a known number. When income swings from ₹30,000 one month to ₹1,40,000 the next, that same advice breaks down in two ways.
First, people tend to anchor spending to good months. A big client payment feels like the new normal, so lifestyle costs rise. Second, lean months then force a scramble: delayed bills, credit card balances carried forward, or a dip into money meant for something else. The problem is rarely the total yearly income. It is the timing.
An irregular income budget fixes the timing problem. Instead of matching spending to each month’s receipts, you separate the two. Receipts go into one place, and a steady, planned amount comes out. The rest of this guide explains exactly how to set that up.
How to Budget an Irregular Income: The 5-Step System
The system below works for freelancers, doctors in private practice, small traders, sales staff on commission and anyone with seasonal earnings. It needs two bank accounts and about 30 minutes a month.
Step 1: Find your real yearly average
Pull your bank statements for the last 12 months and add up every business receipt. Divide by 12. If you are new to freelancing, use a conservative estimate based on signed work only. Also note your three weakest months, because they show how deep a bad patch can get.
Step 2: List your essential monthly costs
Essentials are costs you must pay even in your worst month: rent or home loan EMI, groceries, utilities, insurance premiums, school fees and minimum loan payments. If you have never done this, first track your monthly expenses for two or three months. This number is your survival floor.
Step 3: Open a holding account
Keep a separate savings account that receives all client payments and nothing else. Your everyday account then gets one transfer a month, like a salary credit. This single habit stops a large payment from quietly turning into extra spending.
Step 4: Pay yourself a fixed salary
Set your monthly salary below your average take-home income after the tax reserve. A margin of about 15% works for most people. The salary must at least cover essentials. Inside that salary you can use any method you like, such as the 50/30/20 rule or zero-based budgeting.
Step 5: Build a buffer before you raise spending
The holding account needs a starting balance of at least three months of salary. This buffer is what lets you pay yourself in a month when no client pays you. Only after the buffer is full should surplus go to investments or lifestyle upgrades.
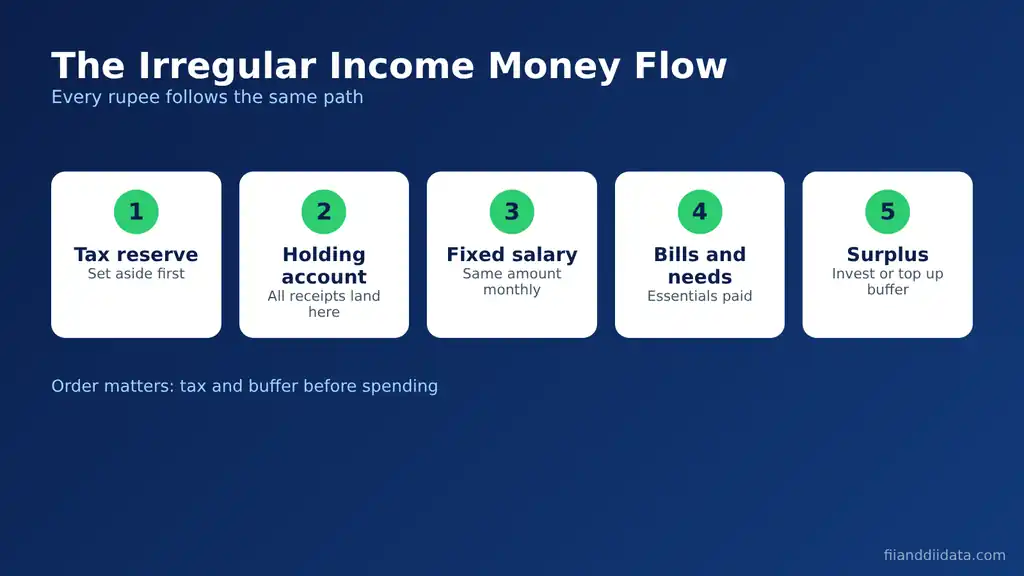
The steps sound simple, but the numbers decide whether the system holds. The next section runs a full year through it.
A Worked Example: 12 Months of Freelance Income
Take Riya, a freelance designer in Pune (an illustrative case). Her receipts in FY 2025-26 ranged from ₹30,000 to ₹1,40,000 a month and totalled ₹8,80,000, an average of about ₹73,333. Her essential costs are ₹38,000 a month. Her three weakest months averaged only ₹35,000, which is below her essentials. Without a system, those months would mean borrowing.
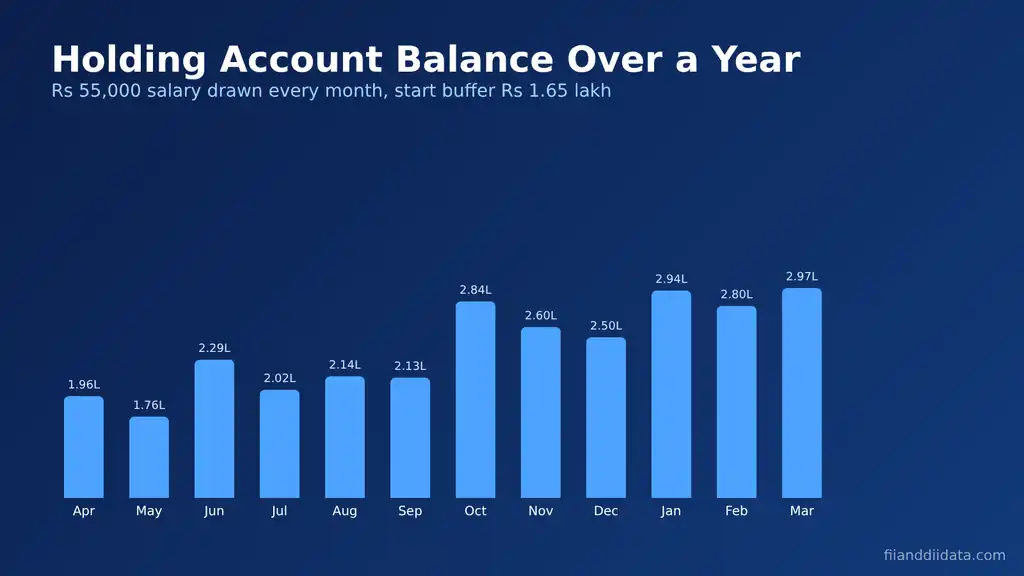
She keeps 10% of every receipt as a tax reserve. This rate is only an assumption for the example; your actual rate depends on your income, regime and deductions. After the reserve, her average take-home is ₹66,000. She sets her salary at ₹55,000, about 83% of that average, and starts with a buffer of ₹1,65,000 (three months of salary).
| Month | Receipts (₹) | Tax reserve 10% (₹) | Salary drawn (₹) | Holding balance (₹) |
|---|---|---|---|---|
| Apr | 95,000 | 9,500 | 55,000 | 1,95,500 |
| May | 40,000 | 4,000 | 55,000 | 1,76,500 |
| Jun | 1,20,000 | 12,000 | 55,000 | 2,29,500 |
| Jul | 30,000 | 3,000 | 55,000 | 2,01,500 |
| Aug | 75,000 | 7,500 | 55,000 | 2,14,000 |
| Sep | 60,000 | 6,000 | 55,000 | 2,13,000 |
| Oct | 1,40,000 | 14,000 | 55,000 | 2,84,000 |
| Nov | 35,000 | 3,500 | 55,000 | 2,60,500 |
| Dec | 50,000 | 5,000 | 55,000 | 2,50,500 |
| Jan | 1,10,000 | 11,000 | 55,000 | 2,94,500 |
| Feb | 45,000 | 4,500 | 55,000 | 2,80,000 |
| Mar | 80,000 | 8,000 | 55,000 | 2,97,000 |
| Total | 8,80,000 | 88,000 | 6,60,000 | Gain: 1,32,000 |
Three things stand out. Riya never missed a salary, even in July when only ₹30,000 came in. Her buffer never fell below ₹1,65,000. And she ended the year with ₹1,32,000 more than she started, which she can now invest or use to raise next year’s salary.
Her ₹55,000 salary is split as ₹38,000 for essentials, ₹8,000 for a monthly SIP and ₹9,000 for wants. Because the salary is fixed, the SIP never has to be paused in a bad month. The tax reserve of ₹88,000 sits aside, which brings us to the part most freelancers get wrong.
Tax Planning When Your Income Is Irregular
Salaried people have tax deducted by the employer. Freelancers and business owners usually have to pay it themselves, during the year, as advance tax. From 1 April 2026, the Income-tax Act, 2025 governs this. Section 404 says advance tax applies when the tax payable for the year is ₹10,000 or more.
Section 408 sets four instalments. By 15 June you must have paid at least 15% of the year’s advance tax, by 15 September at least 45%, by 15 December at least 75%, and the full amount by 15 March. People who declare income under the presumptive scheme referred to in that section pay the whole amount by 15 March instead. Interest applies on shortfalls, so check your case with a chartered accountant.
Suppose your estimated tax for tax year 2026-27 is ₹60,000. As of 7 November 2026, the next date is 15 December 2026. Here is the schedule.
| Due date | Minimum paid so far | Cumulative amount (₹) | Instalment due (₹) |
|---|---|---|---|
| 15 June 2026 | 15% | 9,000 | 9,000 |
| 15 September 2026 | 45% | 27,000 | 18,000 |
| 15 December 2026 | 75% | 45,000 | 18,000 |
| 15 March 2027 | 100% | 60,000 | 15,000 |
The tax reserve in your holding account makes these dates easy. If the reserve grows larger than your actual tax, as in Riya’s case, the extra simply moves back into the buffer after you file. With tax covered, you can plan each month by type.
What to Do in Lean and Strong Months
Your salary stays the same, but your decisions should not. A simple playbook removes the guesswork.
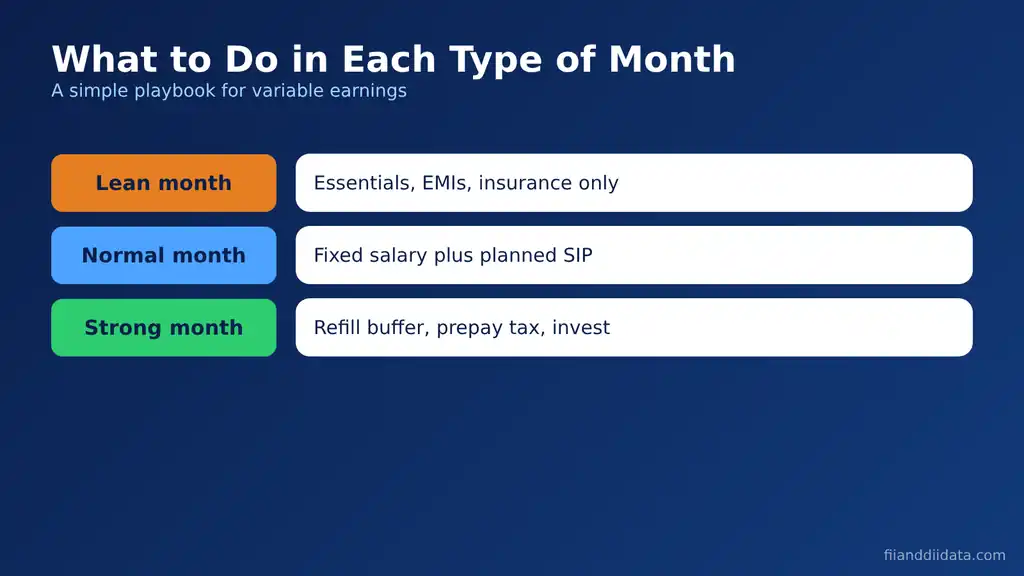
Lean month (receipts below salary)
Draw your normal salary from the buffer. Delay large optional purchases. If the buffer falls below two months of salary, cut wants for the next month and follow up on pending invoices.
Normal month (receipts close to average)
Draw your salary, keep the SIP running and make no changes. Most months should feel boring, which is the point.
Strong month (receipts well above average)
Top up the tax reserve first. Then refill the buffer to its target. Anything left can go to a lump-sum investment, a loan prepayment or a planned goal. Avoid raising your salary after a single good month; review it once a year instead.
Once the buffer is steady, the next question is where long-term savings should go.
Saving and Investing With an Irregular Income
The holding account buffer covers income gaps. It is not the same as an emergency fund, which covers events like a hospital bill or a broken laptop. Self-employed people usually need a larger emergency fund than salaried staff because there is no paid leave or employer cover. A common target is six months of essentials; for Riya that is 6 x ₹38,000 = ₹2,28,000. Our guide on how to build an emergency fund covers where to keep it.
For long-term saving, choose products that accept flexible contributions. A Public Provident Fund account, for example, needs only ₹500 a financial year and accepts up to ₹1,50,000, paid as a lump sum or in any number of instalments, according to Canara Bank’s PPF page (accessed 7 November 2026). That suits uneven earnings well: a small base amount in lean years and larger deposits after strong months. Rates and rules change, so check the current terms before you invest.
Mutual fund SIPs also work, as long as the SIP is paid from your fixed salary rather than from receipts. You can add a lump sum after a strong month. Even with a good structure, a few habits can undo the plan.
Mistakes to Avoid When You Budget an Irregular Income
- Budgeting from your best month. One big project is not your income. Use the 12-month average.
- Mixing business and personal money. Without a holding account, you cannot see how much is truly free to spend.
- Ignoring tax until March. Missing advance tax dates adds interest and a large single bill.
- Using credit cards to cover gaps. Card interest can wipe out months of savings. Your buffer exists for this.
- Pausing SIPs in every bad month. If the SIP comes from a fixed salary, there is no reason to stop it.
- Raising lifestyle costs after one strong quarter. Review your salary once a year, using full-year data.
- Skipping insurance. A health emergency during a lean month can drain both the buffer and the emergency fund.
Avoiding these mistakes matters more than finding the perfect method. The checklist below turns the full system into a routine.
Your Irregular Income Budget Checklist
- Add up 12 months of receipts and find the monthly average.
- List essential costs and confirm your salary covers them.
- Open a separate holding account for all client payments.
- Choose a tax reserve rate with your accountant and move it aside on every receipt.
- Set a fixed salary about 15% below your average take-home.
- Build a buffer of three months of salary before raising spending.
- Build a separate emergency fund of about six months of essentials.
- Mark 15 June, 15 September, 15 December and 15 March for advance tax.
- Run SIPs from your salary and add lump sums after strong months.
- Review the salary once a year using full-year figures.
If you also want a template for the salary side, our step-by-step guide to a monthly budget works well inside this system. You can find more money guides on the FIIAndDIIData.com blog.
FAQ
How do I budget an irregular income?
Send all payments to one holding account, set aside tax, and pay yourself a fixed monthly salary that is below your 12-month average take-home income. Keep at least three months of salary in the holding account as a buffer.
How much emergency fund does a freelancer need?
Many planners suggest about six months of essential expenses for self-employed people, kept separate from the income buffer. Someone with essentials of ₹38,000 a month would aim for about ₹2,28,000.
Do freelancers in India have to pay advance tax?
Yes, if the tax payable for the year is ₹10,000 or more under Section 404 of the Income-tax Act, 2025. Instalments are due by 15 June, 15 September, 15 December and 15 March, with presumptive taxpayers paying by 15 March.
What is the best budgeting method for variable income?
A fixed-salary system with a holding account works best for most people. Inside the fixed salary you can use the 50/30/20 rule or zero-based budgeting, because the amount no longer changes each month.
Can I run a SIP if my income is irregular?
Yes. Pay the SIP from your fixed monthly salary, not from client receipts, so it continues in lean months. Add lump-sum investments after strong months once your buffer is full.
The Bottom Line
An irregular income is harder to manage than a salary, but it is not harder to save from once you separate earning from spending. A holding account, a fixed salary below your average, a three-month buffer and a tax reserve turn uneven receipts into a predictable monthly budget.
The system will not raise your income, and a long dry spell can still test it. That is why the buffer and the emergency fund are kept separate. Your practical next step: pull the last 12 months of bank statements this week and calculate your true average before you set your salary.
Sources: Income Tax Department, Section 408 (advance tax instalments); Income Tax Department, Section 404 (₹10,000 threshold); PIB, NITI Aayog report on the gig economy, 27 June 2022; Canara Bank, Public Provident Fund. All accessed 7 November 2026.
Disclaimer: This article is for educational purposes only and is not investment advice. Please consult a SEBI-registered advisor before making investment decisions.