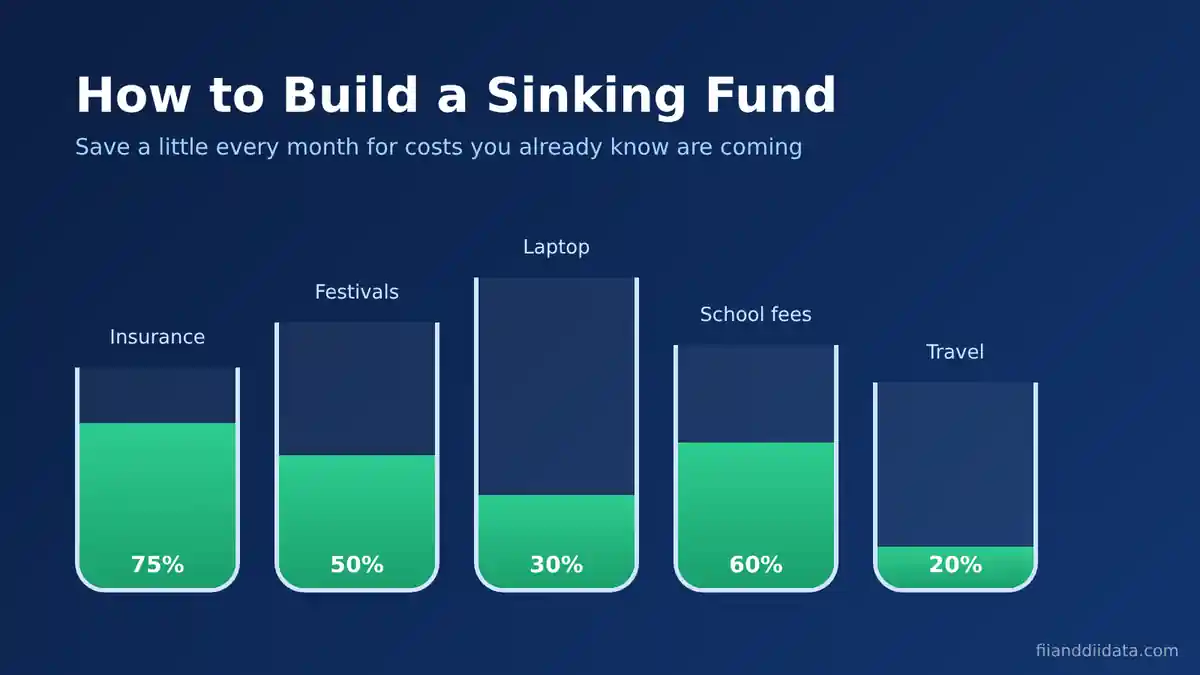
Wondering how to build a sinking fund? List the big expenses you already know are coming, divide each one by the months left, and move that amount into a separate account every month. A ₹18,000 car insurance renewal due in 12 months needs just ₹1,500 a month. Do this for every planned cost and festival bills, school fees and gadget upgrades stop landing on your credit card.
Key Takeaways
- A sinking fund is money you set aside every month for a known, planned expense.
- Monthly saving = target amount ÷ months left. Start early and the monthly figure stays small.
- Keep one sinking fund for each goal, separate from your emergency fund and daily spending account.
- Short goals suit a savings account or recurring deposit; India Post listed 4% on savings and 6.7% on RD (page updated 30 October 2026).
- Automate the transfer on salary day and review the plan once a month.
Table of contents
- What Is a Sinking Fund?
- Sinking Fund vs Emergency Fund
- Why a Sinking Fund Matters for Indian Households
- How to Build a Sinking Fund in 5 Steps
- How to Build a Sinking Fund: A Worked Example
- Where to Keep Your Sinking Fund Money
- Common Sinking Fund Mistakes to Avoid
- Sinking Fund Checklist
- Frequently Asked Questions
- The Bottom Line
What Is a Sinking Fund?
A sinking fund is a pool of money you build in small, regular amounts to pay for a specific expense on a date you can predict. The idea comes from corporate finance, where companies set aside money every year to repay a bond or a loan at maturity. In personal finance the logic is the same, only the bills are smaller: insurance premiums, school fees, a new phone, Diwali shopping or a family wedding.
The key word is known. You may not know the exact rupee figure, but you know the expense will come and roughly when. That is what separates a sinking fund from general savings, which have no fixed job, and from an emergency fund, which covers shocks you cannot predict. The next section makes that difference clear.
Sinking Fund vs Emergency Fund
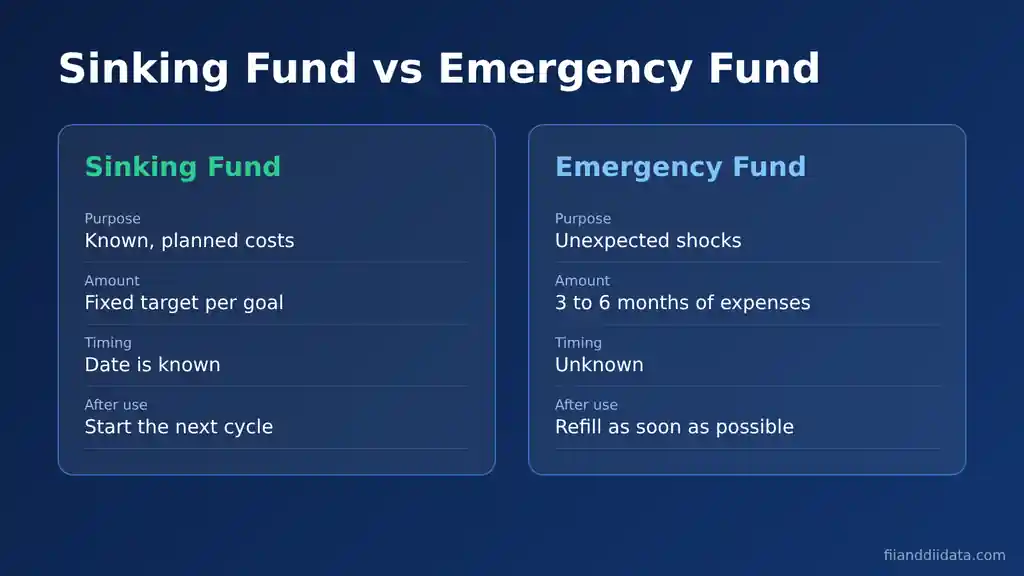
People often mix up the two, and that mix-up is the main reason an emergency fund gets drained by planned spending. Both are cash reserves, but they do opposite jobs.
| Feature | Sinking fund | Emergency fund |
|---|---|---|
| Purpose | Planned, known costs | Unexpected shocks such as job loss or a medical bill |
| Target | Fixed amount per goal | A few months of essential expenses |
| Timing | You know the date | Unknown |
| Number of funds | One per goal, often several | Usually one |
| After you spend it | Start the next cycle | Refill it as soon as possible |
A simple rule helps: if you can put the expense on a calendar, it belongs in a sinking fund. If you cannot, it belongs in the emergency fund. When you keep the two apart, a festival or a laptop upgrade never eats into the money meant for a real crisis.
Why a Sinking Fund Matters for Indian Households
Many Indian expenses are lumpy. Annual health and motor insurance premiums, half-yearly school fees, property tax, festival spending in October and November, and family functions all arrive as single large bills. Your monthly budget handles regular costs like rent and groceries well, but these one-time bills rarely fit inside a single month.
Without a plan, three things usually happen. You dip into the emergency fund, you swipe a credit card and roll over the balance, or you take a short personal loan. Each option costs money or leaves you exposed. A sinking fund turns one painful bill into twelve or twenty-four small, planned transfers.
There is also a behavioural benefit. When money for a goal sits in its own labelled pot, you stop treating your savings account balance as spending money. It becomes easier to say no to an impulse purchase when you can see that the cash already has a job. With the reason clear, here is the method.
How to Build a Sinking Fund in 5 Steps
The method below works whether you earn ₹25,000 or ₹2.5 lakh a month.
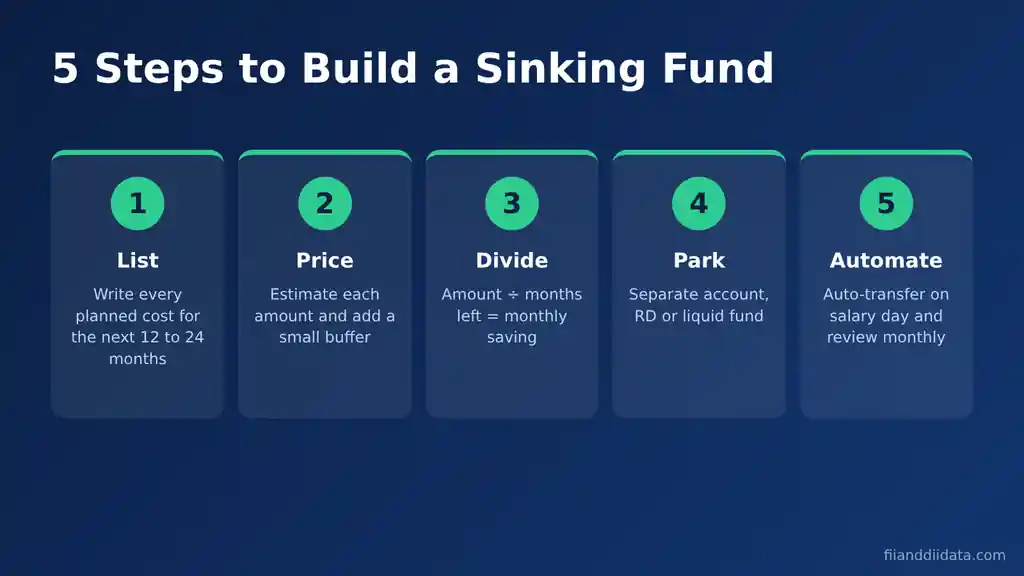
Step 1: List every planned expense for the next 12 to 24 months
Go through last year’s bank and card statements. Note every large, non-monthly payment: insurance renewals, school or college fees, vehicle servicing, gadget replacement, travel, festivals, birthdays, weddings you will attend and annual subscriptions. Add known future costs such as a planned laptop or phone upgrade.
Step 2: Put a price and a due date on each item
Use last year’s bill as a base and add a small buffer of about 5% for price increases. For example, a laptop that costs ₹60,000 today becomes a target of ₹63,000 if you plan to buy it in two years. Write the month you need the money, not the month you think you might shop.
Step 3: Divide to find the monthly amount
Monthly saving = target amount ÷ months remaining. The ₹63,000 laptop over 24 months needs ₹2,625 a month. If a goal is close and the monthly figure looks too high, either push the date back, lower the target, or accept that this one year you will pay part of it from other savings.
Step 4: Choose where to park the money
Open a separate savings account, use a bank’s goal or sub-account feature if it has one, or start a recurring deposit that matures close to the due date. Keep the money away from the account linked to your UPI apps and debit card. The section on where to keep the money compares options in detail.
Step 5: Automate and review monthly
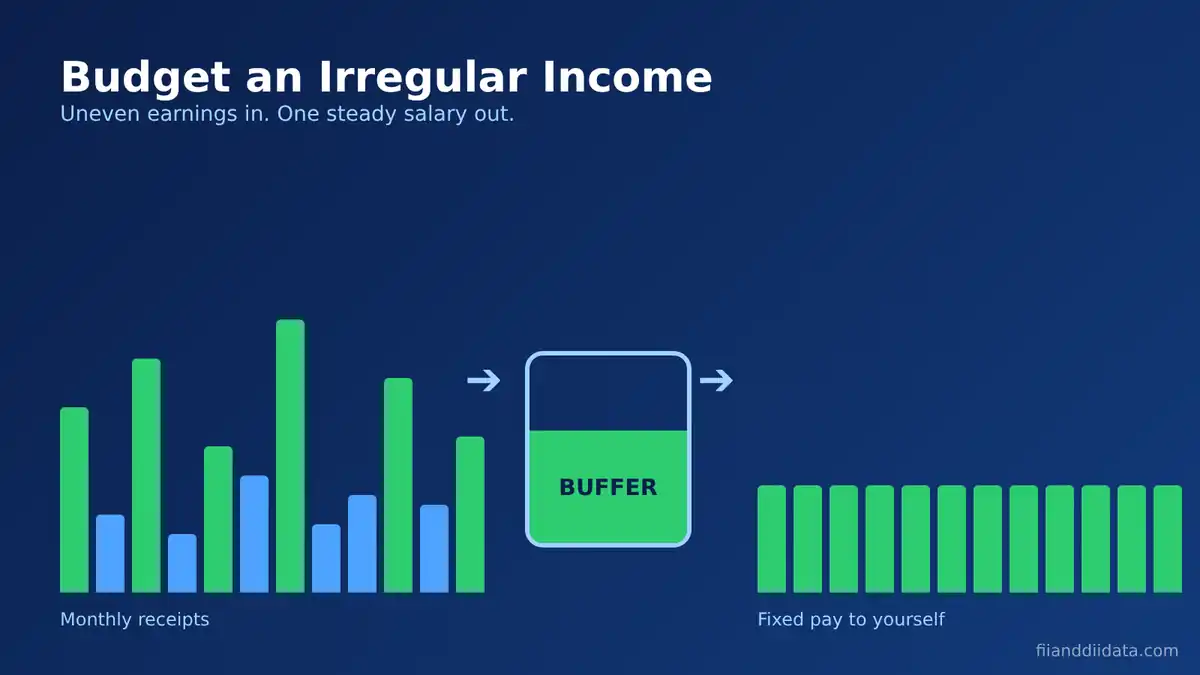
Set a standing instruction or auto-transfer for the day after your salary credit. Once a month, check each fund’s balance against the plan. If your income varies, read our guide on budgeting on an irregular income and fund your sinking goals in good months first.
The steps are simple on paper. The worked example below shows what they look like for a real family budget.
How to Build a Sinking Fund: A Worked Example
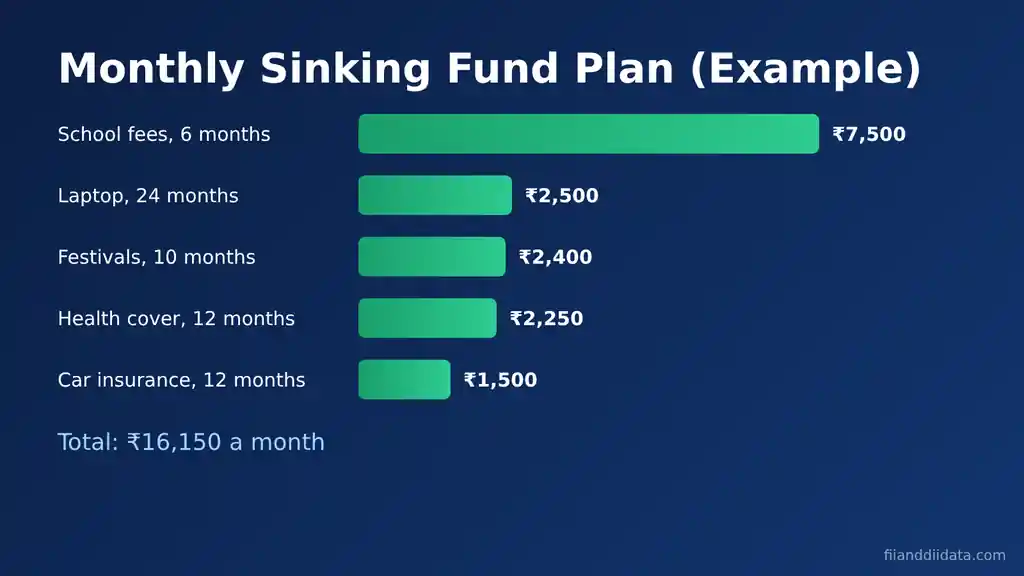
Take a salaried family in a metro that has five planned costs over the next two years. The amounts below are illustrative, not prices from any provider.
| Goal | Target (₹) | Months left | Monthly saving (₹) |
|---|---|---|---|
| Child’s school fees (next term) | 45,000 | 6 | 7,500 |
| Laptop replacement | 60,000 | 24 | 2,500 |
| Diwali and festival spending | 24,000 | 10 | 2,400 |
| Family health insurance premium | 27,000 | 12 | 2,250 |
| Car insurance renewal | 18,000 | 12 | 1,500 |
| Total | 1,74,000 | 16,150 |
The family needs to set aside ₹16,150 a month to pay every one of these bills in cash. Notice how the school fee, with only six months left, takes almost half the total. Had the family started a year earlier, that line would have been ₹2,500 a month instead of ₹7,500. Starting early is the single biggest lever you have.
If ₹16,150 does not fit, rank the goals. Insurance and school fees come first because missing them has real costs. The laptop and festival budget can be trimmed or delayed. A framework like the 50-30-20 budgeting rule can help you see how much of your take-home pay can go to savings goals in the first place.
How to build a sinking fund with interest: does the return matter?
Interest helps, but less than people expect over short periods. Assume the laptop money earns 6% a year, compounded monthly, purely as an illustration. To reach ₹60,000 in 24 months you would need about ₹2,359 a month instead of ₹2,500. That saves roughly ₹141 a month, or about ₹3,378 over two years. Useful, but the habit of saving matters far more than the rate. Pick a safe, easy-to-access option first and chase returns second.
Where you park the money decides both that small return and how safely you can reach it when the bill arrives.
Where to Keep Your Sinking Fund Money
A sinking fund has a fixed date, so safety and access matter more than returns. Equity mutual funds or stocks are a poor fit for goals under three years because prices can fall just when you need the money.
| Option | Rate or return | Best for | Watch out for |
|---|---|---|---|
| Separate bank savings account | Varies by bank | Goals under 6 months, frequent top-ups | Low rate on many banks; check minimum balance rules |
| Bank recurring deposit | Varies by bank and tenure | Goals 6 to 24 months away with a fixed monthly amount | Penalty on premature closure |
| Post Office Savings Account | 4.0% p.a. | Small, flexible goals | Rate set by the government, reviewed periodically |
| Post Office Recurring Deposit | 6.7% p.a., compounded quarterly | Longer goals with fixed monthly saving | Check tenure and premature closure rules before using it for short goals |
| Post Office Time Deposit | 6.9% to 7.5% p.a., by tenure | A lump sum already saved for a dated goal | Money is locked for the chosen term |
| Liquid or overnight mutual fund | Market-linked, not guaranteed | Larger balances held for a few months | Not a bank deposit; returns can vary |
The Post Office figures above come from the India Post savings schemes page, which showed them as current on 8 November 2026. For mutual funds, SEBI’s categorisation circular of 26 February 2026 defines a liquid fund as one that invests only in debt and money market securities with maturity of up to 91 days, and an overnight fund as one that holds securities maturing in one day. These are lower risk than other debt funds, but they are still market-linked and are not covered by deposit insurance.
Bank deposits, on the other hand, carry insurance from the Deposit Insurance and Credit Guarantee Corporation. As per the DICGC guide, each depositor is insured up to ₹5,00,000 per bank, covering principal and interest together. If your combined sinking funds and other deposits at one bank cross that figure, consider spreading them across banks. Interest earned on bank and post office deposits is added to your income and taxed as per your slab, so factor that into the final amount.
Once the money has a home, the bigger risk is how you manage it. These are the mistakes we see most often.
Common Sinking Fund Mistakes to Avoid
- Mixing it with the emergency fund. One pot for everything means a festival can wipe out your crisis cover.
- Keeping it in your spending account. If UPI and debit card payments draw from the same balance, the money will leak.
- Starting too late. As the school-fee example showed, a short runway triples the monthly amount.
- Ignoring price rises. Add a buffer of around 5% for goods and services that get costlier every year.
- Taking risk with short-term money. Equity is not suitable for a bill due in six months.
- Creating too many tiny funds. Ten pots of ₹300 each are hard to track. Group small items such as gifts and subscriptions into one fund.
- Not restarting after spending. Annual costs repeat. The month after you pay a premium, restart the transfer for next year.
Avoiding these mistakes keeps the system working year after year. The checklist below pulls everything together. For goal-specific plans, see our guide on saving for a vacation.
Sinking Fund Checklist
- List every non-monthly expense from last year’s statements.
- Add known future purchases for the next 24 months.
- Set a target amount with a 5% buffer and a due month for each.
- Calculate the monthly amount: target ÷ months left.
- Rank goals if the total is more than you can afford.
- Open a separate account, sub-account or recurring deposit.
- Set an auto-transfer for the day after salary credit.
- Keep your emergency fund in a different place.
- Review balances on the same date each month.
- Restart each annual fund the month after you use it.
Frequently Asked Questions
What is a sinking fund in personal finance?
A sinking fund is money you save in small, regular amounts for a specific planned expense, such as an insurance premium, school fees or a new phone. Because the cost and its timing are known in advance, you can spread it over many months instead of paying it from one salary or a credit card.
How to build a sinking fund if my income is small?
Start with one or two essential goals, such as an insurance renewal or school fees, and save whatever amount fits, even ₹500 a month. Begin as early as possible so the monthly figure stays low, keep the money in a separate account, and add new goals only when your income or savings capacity grows.
Where should I keep my sinking fund money in India?
For goals under a year, a separate savings account or a bank recurring deposit works well. India Post listed 4% on its savings account and 6.7% on its recurring deposit on a page updated 30 October 2026. Larger balances held for a few months can go to a liquid fund, but those returns are not guaranteed.
Is a sinking fund the same as an emergency fund?
No. A sinking fund pays for expenses you can predict and put on a calendar. An emergency fund covers shocks you cannot predict, such as a job loss or a medical bill. Keeping them separate stops planned spending from draining your safety net.
How many sinking funds should I have?
Most households manage well with three to six funds. Create separate funds for large or important goals such as insurance, school fees and travel, and group small, similar costs such as gifts and subscriptions into a single fund so tracking stays simple.
The Bottom Line
Learning how to build a sinking fund is less about finding the best interest rate and more about planning ahead. List the costs you already know are coming, divide each by the months left, and move that money into a separate place every month. Big bills then arrive as planned payments rather than shocks.
The method will not make expenses smaller, and it does need discipline when other wants compete for the same rupees. Your next step is simple: open last year’s bank statement today, pick the next three large bills, and set up one auto-transfer this week. You can find more of our personal finance guides on the blog.
Sources: India Post, Savings Schemes; SEBI, Categorization and Rationalization of Mutual Fund Schemes (26 February 2026); DICGC, A Guide to Deposit Insurance.
Disclaimer: This article is for educational purposes only and is not investment advice. Please consult a SEBI-registered advisor before making investment decisions.