Financial planning for beginners starts with three numbers: what you own, what you owe and what you need money for, with a date and a price next to each goal. Everything else, from budgeting to insurance to SIPs, follows from those numbers. The case for doing it now is simple: retail inflation rose to 5.54% in September 2026, as per data released on 12 October 2026, so goals priced in today’s rupees will cost more by the time you reach them.
Key Takeaways
- A financial plan is a written list of goals, each with a cost, a date and a monthly saving attached.
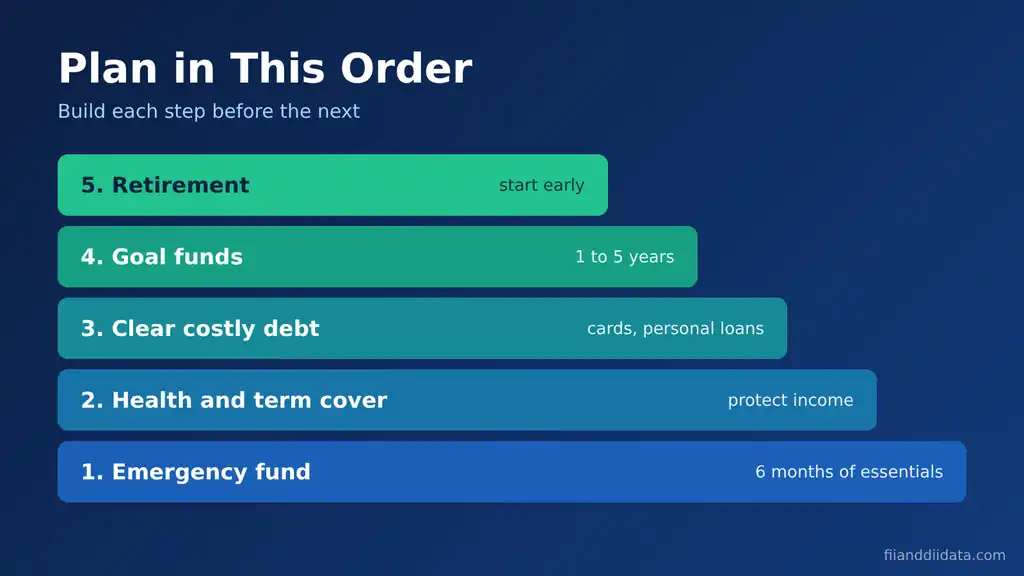
- Build in this order: emergency fund, health and term cover, costly debt, goal funds, retirement.
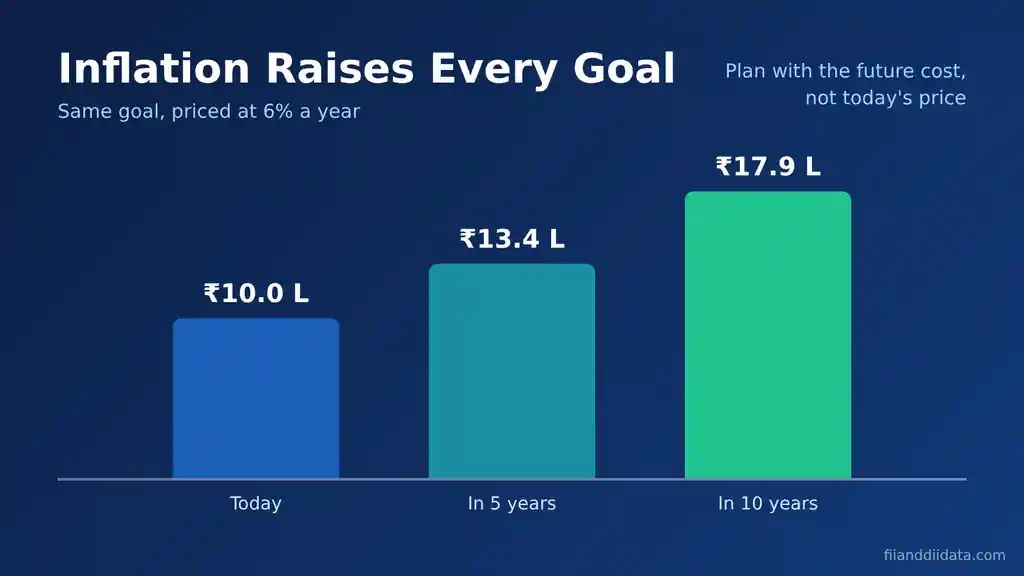
- Price every goal at its future cost; at 6% a year, a ₹10 lakh goal becomes about ₹17.9 lakh in 10 years.
- In our ₹55,000 salary example, ₹13,750 a month (25%) is enough to fund every goal once the steps are put in sequence.
- Review the plan once a year and after any big life event, such as a new job, marriage or a child.
Table of contents
- What is financial planning?
- Why financial planning for beginners matters in 2026
- Financial planning for beginners in 6 steps
- The right order: what to fund first
- Worked example: a ₹55,000 salary plan
- Where to keep money for each goal
- Common mistakes and a yearly checklist
- Frequently asked questions
- The Bottom Line
What Is Financial Planning?
Financial planning is the process of matching your income to your goals over time. A budget answers “where does this month’s salary go?” A financial plan answers a bigger question: “will I have enough money for the things that matter, when they arrive?”
A complete plan covers five areas: cash flow, protection (emergency fund and insurance), debt, goals and retirement. Tax is not a separate goal but a filter you apply to each choice.
How a financial plan differs from a budget
| Point | Monthly budget | Financial plan |
|---|---|---|
| Time frame | One month | 1 to 30+ years |
| Main question | Where does my salary go? | Can I afford my goals on time? |
| Key output | Spending limits by category | Goal list with cost, date and monthly saving |
| Covers risk? | Rarely | Yes: emergency fund and insurance |
| Review | Every month | Once a year and after big life events |
If you have not built a budget yet, start with our guide on how to create a monthly budget, because the plan sits on top of it. Next, here is why the plan matters more this year than usual.
Why Financial Planning for Beginners Matters in 2026
The CPI release for September 2026 put headline retail inflation at 5.54% and food inflation at 7.74%. At that pace, idle money loses buying power every year.
What 5.54% inflation does to your savings
- Buying power: if prices rise 5.54% every year for 10 years, ₹1 lakh kept in cash will buy only what about ₹58,322 buys today.
- Real return: a 1-year post office time deposit pays 6.9%. After 5.54% inflation, the real gain is only about 1.29% a year, before tax.
- Goal cost: a goal that costs ₹10 lakh today will cost about ₹13.4 lakh in 5 years and ₹17.9 lakh in 10 years at 6% inflation.
We use 6% as a round planning figure close to recent inflation. Education and medical costs often rise faster, so use 8% to 10% for those goals.
Financial Planning for Beginners in 6 Steps
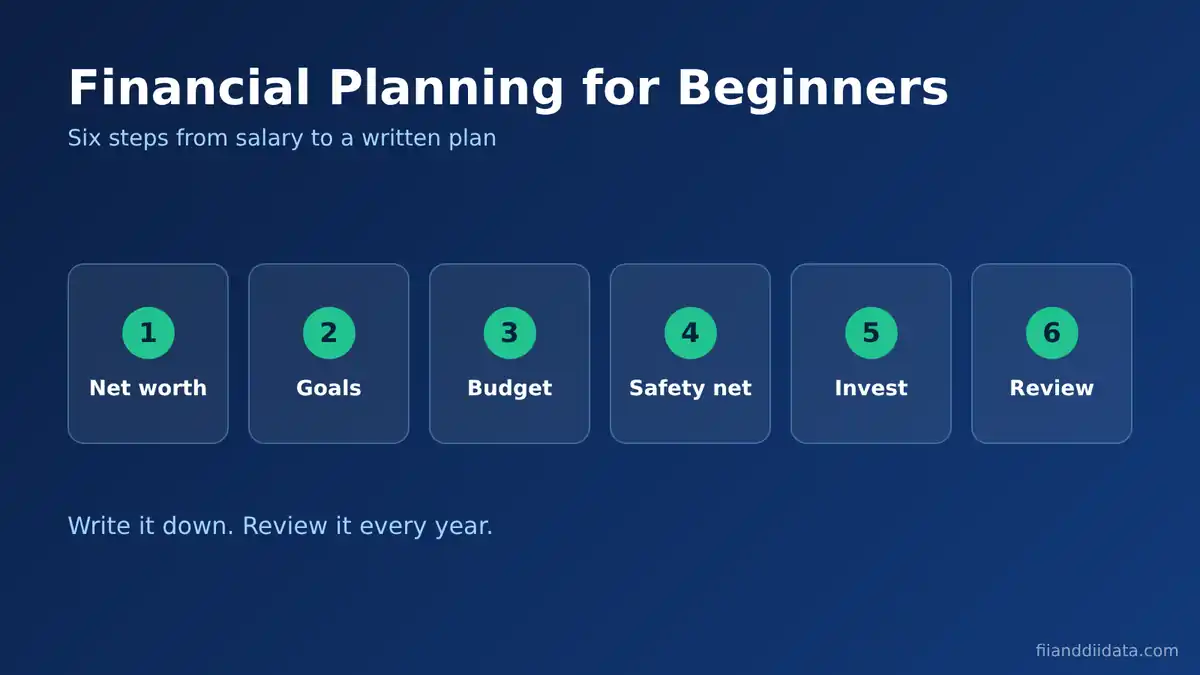
Step 1: Work out your net worth
Net worth is everything you own minus everything you owe. Add bank balances, EPF, PPF, mutual funds, shares and gold. Subtract loans and card dues. Leave out the house you live in and your vehicle for now; they do not fund goals. The number may be small or negative. That is fine, because it is the starting line you will measure progress from.
Step 2: List goals with a cost and a date
Write down every goal and split them into short term (under 3 years), medium term (3 to 7 years) and long term (over 7 years). Note today’s cost and the target year, then raise the cost for inflation. “Save for a car” is a wish. “₹3 lakh down payment in 2031” is a goal.
Step 3: Fix your monthly cash flow
Use take-home pay, not gross salary. Cap essentials, set a limit for wants and decide one saving amount that leaves your account the day after salary. Our guide on saving a fixed amount every month covers the habits that make this stick.
Step 4: Build your safety net
Your safety net has three parts: an emergency fund of 3 to 6 months of essential costs, a health insurance policy of your own (not only the employer’s group cover, which ends when you leave the job) and term life insurance if anyone depends on your income. A common rule of thumb for term cover is 10 to 15 times your annual income.
Step 5: Invest for each goal separately
Match the product to the time frame. Money needed within three years should not depend on the stock market. Money needed after seven years can take equity risk, because time smooths out bad years. Run one SIP or deposit per goal so you always know which money belongs to which goal.
Step 6: Review once a year
Once a year, update net worth, check each goal, raise SIPs with your increment and recheck insurance. Also review after a job change, marriage or a child. Doing these steps in the right order matters just as much.
The Right Order: What to Fund First
Beginners often try to fund everything at once and end up with many half-filled pots. Fund in layers instead, where each layer protects the one above it.
| Priority | What to fund | Target | Why it comes here |
|---|---|---|---|
| 1 | Starter emergency fund | 1 month of essentials | Stops small shocks from becoming debt |
| 2 | Health and term insurance | Own health policy; term cover if you have dependants | One hospital bill can wipe out years of saving |
| 3 | Costly debt | Clear credit card dues and personal loans | Card interest is far higher than any safe return |
| 4 | Full emergency fund | 3 to 6 months of essentials | Covers job loss without selling investments |
| 5 | Goal funds and retirement | One SIP or deposit per goal | Now the money can stay invested for its full term |
One exception: start a small retirement SIP from your first salary, even ₹1,000, alongside the earlier layers. Time does most of the work in retirement saving, and every year you wait makes the monthly amount bigger.
Low-cost debt can wait
An education or home loan at a moderate rate does not need early repayment before your emergency fund is ready; just pay the EMI on time. Our 12 personal finance rules for Indian earners cover debt habits in more detail.
Worked Example: A ₹55,000 Salary Plan
Take Priya, 28, a software tester in Pune who takes home ₹55,000 a month and has an education loan. The figures are an illustration, not a recommendation.
Her starting net worth
Assets: savings account ₹60,000, EPF ₹1,20,000, mutual funds ₹25,000 and gold ₹45,000, a total of ₹2,50,000. Liabilities: education loan outstanding ₹1,20,000. Net worth: ₹1,30,000.
Her monthly split
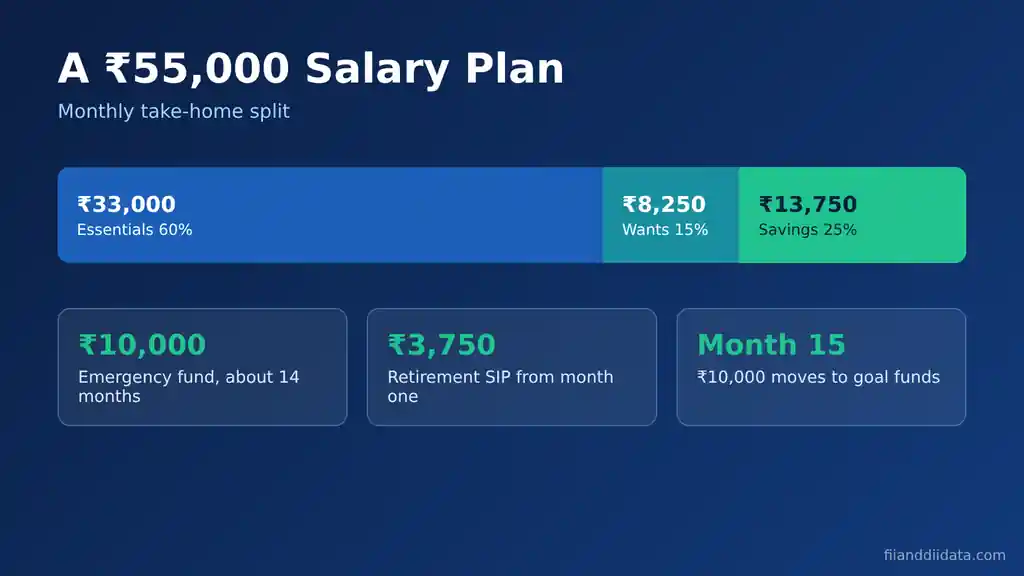
Essentials, including rent, food, travel, the loan EMI and insurance premiums, cost ₹33,000 (60%). Wants get ₹8,250 (15%). That leaves ₹13,750 (25%) for saving, which she splits into ₹10,000 for the emergency fund and ₹3,750 for a retirement SIP.
Her goals, priced for inflation
| Goal | Cost today | When | Future cost (6% inflation) | Monthly saving needed |
|---|---|---|---|---|
| Emergency fund (6 × ₹33,000) | ₹1,98,000 | Within 14 months | ₹1,98,000 | ₹10,000 (₹60,000 already saved) |
| Car down payment | ₹3,00,000 | 3 years | ₹3,57,305 | ₹8,896 at 7% return |
| Car down payment (moved to 5 years) | ₹3,00,000 | 5 years | ₹4,01,468 | ₹5,575 at 7% return |
| Retirement at 60 | Open-ended | 32 years | Not fixed | ₹3,750 grows to about ₹1.05 crore at 10% return |
The table shows the trade-off every plan faces. A three-year car goal needs ₹8,896 a month, which she cannot fund while building the emergency fund. Moving the goal to five years and starting it only after the emergency fund is complete solves this. From month 15, the ₹10,000 moves to the car fund. With 46 months left, the five-year target needs about ₹7,590 a month, so she can add the remaining ₹2,410 to her retirement SIP.
Reading the retirement number honestly
₹1.05 crore sounds large, but at 6% inflation it is worth about ₹16.3 lakh in today’s money, which is why she must raise the SIP with every increment. For term cover, 10 to 15 times her annual take-home of ₹6.6 lakh points to ₹66 lakh to ₹99 lakh, so a ₹1 crore term plan would cover the range.
Where to Keep Money for Each Goal
Each goal needs a home that matches its time frame. Government small savings rates for October to December 2026 were left unchanged by the Ministry of Finance in an office memorandum dated 30 September 2026. The table uses rates shown on India Post’s savings schemes page.
| Time frame | Options | Rate or risk (Oct to Dec 2026) | Fits which goal |
|---|---|---|---|
| Any day | Post Office Savings Account, bank savings or sweep-in deposit | 4.0% at the post office; banks vary | Emergency fund |
| 1 to 3 years | Post Office Time Deposit, bank FD | 6.9% to 7.5% for post office TDs by tenure | Short goals, insurance premium fund |
| Regular monthly saving | 5-year Recurring Deposit | 6.7%, compounded quarterly | Goals 3 to 5 years away |
| 15 years | Public Provident Fund | 7.1%, compounded yearly | Retirement, child’s education |
| 7 years or more | Equity mutual funds through SIP | Market-linked; can fall in bad years | Retirement, long goals |
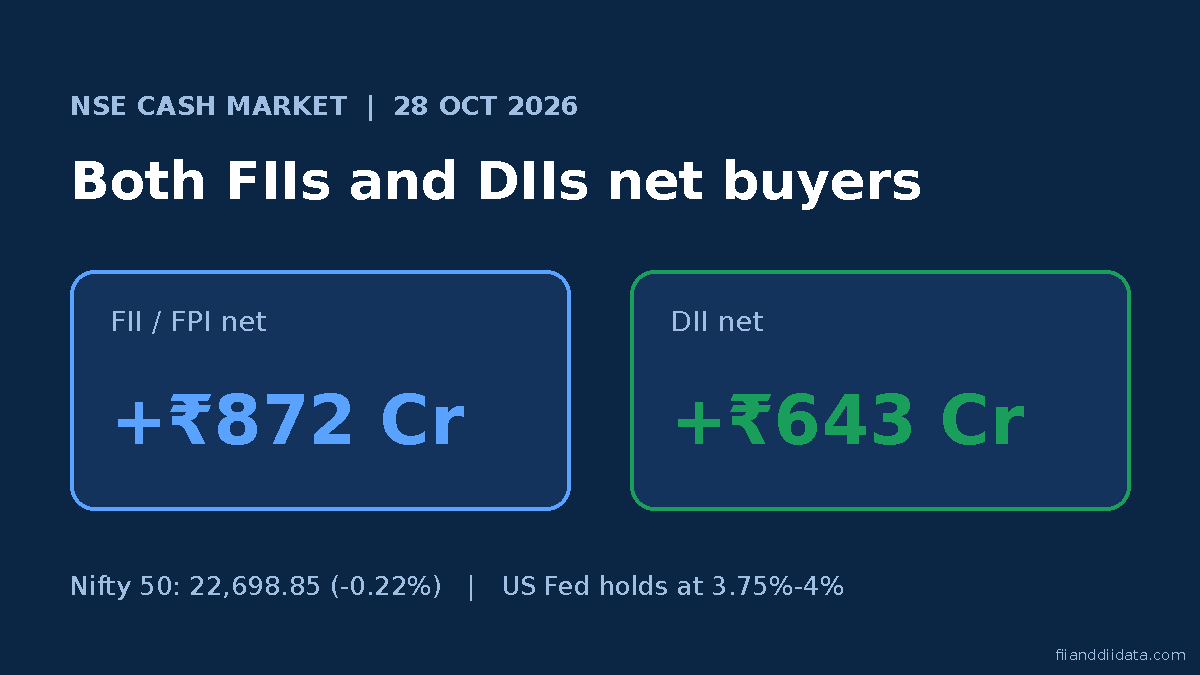
SIPs have become the main route for Indian households into equities; our September 2026 SIP flow report tracks how much money arrives each month. If you invest in equity funds, it also helps to understand who moves the market. Our daily FII and DII data shows how foreign and domestic institutions buy and sell, which explains many of the swings you will see in your SIP value.
Add tax to the plan
Under the new tax regime slabs listed on the Income Tax Department’s portal, a rebate of up to ₹60,000 under Section 87A applies when taxable income does not exceed ₹12 lakh. So many salaried beginners pay little or no tax and should pick investments for the goal, not for a deduction. Compare both regimes each year before you file.
Common Mistakes and a Yearly Checklist
- Buying insurance as an investment. Endowment and money-back plans mix cover and saving and often deliver little of both. Keep term cover and investing separate.
- Planning in today’s prices. A goal priced without inflation will fall short, sometimes by 40% or more over a decade.
- Using the emergency fund for wants. A sale or a trip is not an emergency. Refill the fund first if you ever dip into it.
- Never raising the SIP. A flat SIP shrinks in real terms every year. Raise it with each increment.
- Taking tips as advice. If you want professional help, check that the adviser is registered with SEBI and ask how they are paid before you share details.
Financial planning for beginners: yearly review checklist
- Has net worth gone up since last year? If not, why?
- Is the emergency fund still equal to 6 months of current essential costs?
- Does your own health policy still cover a realistic hospital bill in your city?
- Does term cover still equal 10 to 15 times income, given any new dependants or loans?
- Is each goal on track, with costs updated for inflation?
- Did every SIP rise with your increment?
- Are nominations updated on bank accounts, EPF, PPF, mutual funds and insurance?
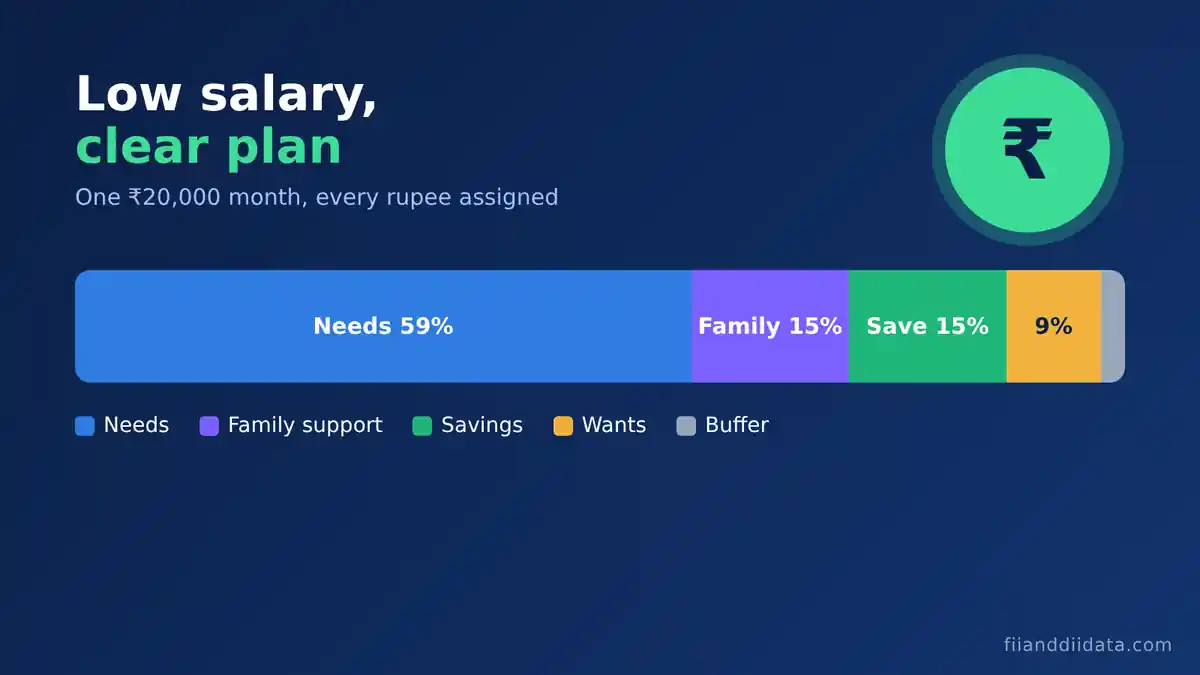
If you earn less than Priya and the numbers above feel out of reach, our guide on managing expenses on a small salary shows the same ideas on a ₹20,000 income.
Frequently Asked Questions
How do I start financial planning for beginners?
Start by working out your net worth, then list each goal with today’s cost and the year you need it. Fix a monthly saving from take-home pay, build an emergency fund and buy health and term cover, then invest for each goal separately and review the plan once a year.
What are the 5 basic steps of financial planning?
The core steps are: assess your current position (income, spending and net worth), set goals with a cost and date, make a cash flow plan, protect yourself with an emergency fund and insurance, and invest for each goal. A sixth step, reviewing the plan every year, keeps it current.
How much of my salary should I save as a beginner?
Aim for 20% to 25% of take-home pay if your essentials allow it. In our ₹55,000 example, 25% or ₹13,750 a month funds an emergency fund, a car goal and a retirement SIP once they are done in sequence. If that is too much, start with 10% and raise it with every increment.
Should I invest or build an emergency fund first?
Build at least one month of essential costs as a starter emergency fund and buy health cover before investing for medium-term goals. A small retirement SIP can start alongside, because time matters most for long-term money.
Do I need a financial planner to make a plan?
Not for a basic plan; a spreadsheet and the steps in this guide are enough. If your finances are complex, such as business income or several dependants, consider a SEBI-registered investment adviser and ask how they charge.
The Bottom Line
A financial plan does not need complex products. It needs a net worth figure, a written list of goals priced for inflation, a fixed monthly saving and the discipline to fund things in the right order: safety first, then goals, with retirement running quietly in the background.
With inflation at 5.54% in September 2026, the cost of waiting is real. Your next step: this weekend, list your assets and loans on one page, write down three goals with a cost and a year, and set up one automatic transfer for the day after salary. Rates and tax rules change, so recheck them on official sites before you act. For more guides on money and markets, visit our blog.
Sources: PIB, CPI press release for September 2026 (12 October 2026); India Post, savings schemes interest rates; Ministry of Finance (Department of Economic Affairs), OM F.No. 1/4/2019-NS on small savings rates for Q3 FY 2026-27 (30 September 2026); Income Tax Department, tax slabs and Section 87A rebate.
Disclaimer: This article is for educational purposes only and is not investment advice. Please consult a SEBI-registered advisor before making investment decisions.