The Sensex is the benchmark index of the BSE, and it tracks the share prices of 30 large, well-established companies listed on the exchange. When news channels say the market is up or down, they often mean the Sensex. This guide explains what it contains, how it is calculated, how it differs from the Nifty 50, and how to read it next to institutional flows, with a worked example using made-up numbers.
Key Takeaways
- The Sensex tracks 30 large companies listed on the BSE and uses a base value of 100 for 1978-79.
- It uses the free-float market capitalisation method, so only shares available for public trading count toward weights.
- The index value equals the total free-float market cap of the 30 stocks divided by an index divisor.
- A point move in the index means little on its own. Percentage change and context matter more.
- Use it as a market thermometer, not as a signal to buy or sell any stock.
- What Is the Sensex?
- Index Constituents and Selection Rules
- How the Sensex Is Calculated
- Sensex vs Nifty 50
- Why This Index Matters for Retail Investors
- Worked Example: A Mini Index With Three Stocks
- How to Read the Index Alongside FII and DII Flows
- Common Mistakes When Reading the Index
- Pros and Cons of the Sensex
- FAQ
- The Bottom Line
What Is the Sensex?
The Sensex is a stock market index. An index is a single number built from the prices of a group of shares, so that you can follow the mood of a whole market without checking every stock. The Sensex covers 30 companies listed on the BSE (formerly the Bombay Stock Exchange). According to the BSE, its base period is 1978-79 with a base value of 100 index points, and the series was first compiled in 1986.
Because the base value is 100, a reading tells you how much the group of 30 companies has grown in total value compared with the base period, after adjustments for corporate actions. It is not a rupee price and you cannot buy the Sensex directly. You can only buy products that track it, such as index funds and ETFs. For a comparison of the two big exchanges and their headline indices, read our guide on NSE vs BSE.
What a Sensex Point Means
A point is one unit of the index. If the index rises by 500 points, that sounds large, but the meaning depends on the starting level. A 500-point rise from a high index level is a smaller percentage move than the same 500 points from a lower level. This is why experienced readers quote the percentage change first and the points second.
Index Constituents and Selection Rules
The index holds 30 stocks. They are chosen to represent the larger and more actively traded companies on the BSE. An Index Committee reviews the list. As per the BSE, the committee meets every quarter, and changes to the list are announced about six weeks before they take effect.
The BSE lists several eligibility conditions for a stock to enter the index. These include a high rank by full market capitalisation, a minimum free-float weight, regular trading on almost every day of the past year, high rankings for number of trades and traded value, and a listing history of at least one year on the BSE. Exact cut-offs can change, so check the BSE website for the current methodology.
Why Only 30 Stocks?
A small basket is easy to calculate and easy to follow. The idea is that 30 large and liquid companies from different sectors can reflect the direction of the wider market. The limit is that 30 stocks cannot capture every segment. Mid-cap and small-cap shares can move very differently from the index, which is why many investors also look at broader indices.
How the Sensex Is Calculated
The BSE uses the free-float market capitalisation method for this index. It replaced the earlier full market capitalisation method with effect from 1 September 2003, according to the BSE. In plain terms, the index gives each company a weight based on the value of the shares that are actually available for trading by the public.
Step 1: Find the Free-Float Market Cap of Each Sensex Stock
For each company, multiply the share price by the number of shares issued to get the full market capitalisation. Then multiply by the free-float factor, which is the share of the company that is freely tradable. Promoter holdings, government stakes and other locked-in shares are excluded from the free float.
Free-float market cap = Share price × Shares issued × Free-float factor
Why Free Float Matters for Sensex Weights
Suppose two companies have the same full market cap, but promoters hold 70% of one and 20% of the other. The second has far more shares available to trade, so it should have a bigger say in an index that aims to show what investors can actually buy. Free-float weighting does exactly that.
Step 2: Divide by the Index Divisor
Add the free-float market caps of all 30 stocks, then divide by the index divisor. The divisor links today’s total back to the base period. The BSE adjusts it when corporate actions or constituent changes would otherwise cause a jump that has nothing to do with market prices.
Sensex = Sum of free-float market caps of the 30 stocks ÷ Index divisor
Because of the divisor, replacing one stock with another does not move the index by itself. Only price changes do. The worked example below shows this with simple numbers.
Sensex vs Nifty 50
The Nifty 50 is the headline index of the NSE and covers 50 companies, while the Sensex covers 30 companies on the BSE. Both are large-cap, free-float indices, so they usually move in the same direction on most days, even if the size of the move differs slightly.
| Point | Sensex | Nifty 50 |
|---|---|---|
| Exchange | BSE | NSE |
| Number of stocks | 30 | 50 |
| Weighting method | Free-float market capitalisation | Free-float market capitalisation |
| Best used for | Quick read of top large caps | Wider large-cap read, widely used in F&O |
Neither index is better in every way. The Nifty 50 has more stocks and is the base for most index derivatives in India, while the BSE benchmark is older and has a long history. If you want to see how institutions are trading alongside these indices, our guide to the difference between FII and DII is a good starting point.
Why This Index Matters for Retail Investors
- Market mood: it gives a quick read on whether large Indian companies are broadly rising or falling.
- Benchmark: you can compare your own portfolio or a mutual fund with the index over the same period.
- Product base: index funds and ETFs can track the Sensex, so the index decides what those products hold.
- Valuation context: you can pair it with measures such as the PE ratio to judge whether the market looks stretched or cheap against its own history.
Next, a worked example makes the formula concrete.
Worked Example: A Mini Index With Three Stocks
All numbers below are made up for teaching. They are not real companies and not real index data. Suppose a mini index holds three companies. Share counts are in crore and values are in ₹ crore.
| Company | Price (₹) | Shares (crore) | Free-float factor | Free-float market cap (₹ crore) |
|---|---|---|---|---|
| A | 500 | 100 | 0.40 | 20,000 |
| B | 1,200 | 50 | 0.55 | 33,000 |
| C | 250 | 400 | 0.25 | 25,000 |
| Total | 78,000 |
Step 1: Free-Float Market Caps and the Divisor
Company A: 500 × 100 × 0.40 = ₹20,000 crore. Company B: 1,200 × 50 × 0.55 = ₹33,000 crore. Company C: 250 × 400 × 0.25 = ₹25,000 crore. The total is 20,000 + 33,000 + 25,000 = ₹78,000 crore.
Suppose the base-period free-float market cap was ₹39,000 crore, and the base value was set at 100. Then the divisor is 39,000 ÷ 100 = 390. The index value is 78,000 ÷ 390 = 200.00.
Step 2: One Stock Rises 10%
Company A’s price rises 10% from ₹500 to ₹550. Its free-float market cap becomes 550 × 100 × 0.40 = ₹22,000 crore. The new total is 22,000 + 33,000 + 25,000 = ₹80,000 crore, so the index is 80,000 ÷ 390 = 205.13.
The index rose 5.13 points, or 2.56%. Company A rose 10%, but the index rose only 2.56% because A holds about 25.6% of the total weight (20,000 ÷ 78,000). Check: 10% × 25.6% = 2.56%. Weights matter more than the number of stocks that moved.
Step 3: A Stock Is Replaced
Now suppose Company C (₹25,000 crore) is replaced by Company D with a free-float market cap of ₹30,000 crore. The total would jump to 80,000 − 25,000 + 30,000 = ₹85,000 crore. If the divisor stayed at 390, the index would leap to 217.95 without any price change. To avoid this, the divisor is reset to 85,000 ÷ 205.1282 = 414.375, so the index stays at 205.13 right after the swap.
On the next day, if D’s price rises 2%, its cap becomes ₹30,600 crore and the total becomes ₹85,600 crore. The index is 85,600 ÷ 414.375 = 206.58, a gain of 0.71%. The divisor keeps changes in membership from creating fake moves.
| Stage | Total free-float cap (₹ crore) | Divisor | Index value |
|---|---|---|---|
| Base setup | 78,000 | 390 | 200.00 |
| A rises 10% | 80,000 | 390 | 205.13 |
| C replaced by D | 85,000 | 414.375 | 205.13 |
| D rises 2% | 85,600 | 414.375 | 206.58 |
How to Read the Index Alongside FII and DII Flows
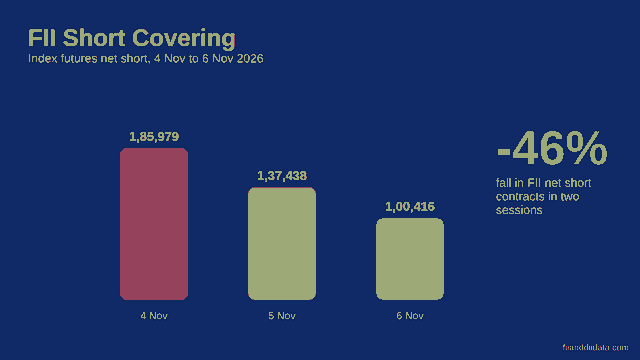
The index tells you what prices did. FII and DII figures tell you who was buying and selling. Foreign portfolio investors (FPIs, also called FIIs) and domestic institutions both trade the large caps that dominate it, so reading the two together gives a fuller picture than either one alone. We publish the daily numbers on our FII DII data today page, and official provisional figures from NSE normally appear after market close.
A Simple Five-Step Routine
- Note the index close and its percentage change for the day.
- Open the end-of-day FII and DII net figures and write both down.
- Check whether the two groups leaned the same way or opposite ways.
- Add the weekly and monthly totals from our monthly FII DII figures to see the trend.
- Keep a short log for ten trading days before you draw any conclusion.
Remember that these are end-of-day records. They describe what already happened and do not predict the next session. To understand how domestic institutions behave, see our explainer on how to read DII data, and visit the home page for the latest FII and DII data.
Common Mistakes When Reading the Index
- Focusing on points instead of percentages. A 600-point move means different things at different index levels.
- Treating the index as the whole market. Thirty stocks cannot show what mid caps or small caps are doing.
- Assuming every stock in the index is equal. Heavier weights move the index more, as the worked example showed.
- Expecting the index to predict your portfolio. Your own holdings may behave very differently.
- Reading one day as a trend. Look at weeks and months, not a single session.
- Using the index as a trading signal. It describes the market and does not tell you when to buy or sell.
Pros and Cons of the Sensex
| Pros | Cons |
|---|---|
| Long history that goes back to the base period of 1978-79 | Only 30 stocks, so it misses mid caps and small caps |
| Free-float method reflects shares that are actually tradable | Large weights in a few companies can dominate daily moves |
| Easy to follow and widely reported | Point moves alone can mislead without the percentage |
| Tracked by index funds and ETFs, so it works as a benchmark | Index rules and constituents change, so the basket is not fixed |
| Useful alongside FII and DII flows for context | Does not show why prices moved or what comes next |
FAQ
What is the Sensex in simple words?
It is an index of 30 large companies listed on the BSE. It is built from their free-float market capitalisation and shows how that group of stocks has moved compared with a base value of 100 set for 1978-79.
How many companies are in the Sensex?
It has 30 companies. The BSE Index Committee reviews the list every quarter, so the names can change over time. Check the BSE website for the current list.
How is the Sensex calculated?
Multiply each stock’s price by its shares issued and free-float factor, add the results for all 30 stocks, and divide the total by the index divisor. The divisor is adjusted for corporate actions and constituent changes.
What is the difference between the Sensex and the Nifty 50?
The Sensex covers 30 companies on the BSE, while the Nifty 50 covers 50 companies on the NSE. Both use free-float market capitalisation and usually move in the same direction.
Can I invest directly in the Sensex?
No. The Sensex is a number, not a product. You can invest in an index fund or ETF that tracks it, and you should read the fund’s offer document and costs first.
The Bottom Line
The Sensex is a simple, long-running gauge of how 30 large BSE companies are doing. Once you know the formula, free-float market cap divided by the index divisor, it stops being a mystery number and becomes a tool you can check yourself. Its main limits are its small basket and its heavy weights in a few big names.
Your next step: for the next ten trading days, note the Sensex percentage change next to the FII and DII net figures in a notebook. That habit will teach you more about the Sensex than any single day’s headline. For more explainers, browse our blog guides.
Sources: BSE, Sensex FAQs; BSE India; NSE India; SEBI. Always check the official sites for current index rules.
Disclaimer: This article is for educational purposes only and is not investment advice. All figures in the worked example are hypothetical. Please consult a SEBI-registered advisor before making investment decisions.