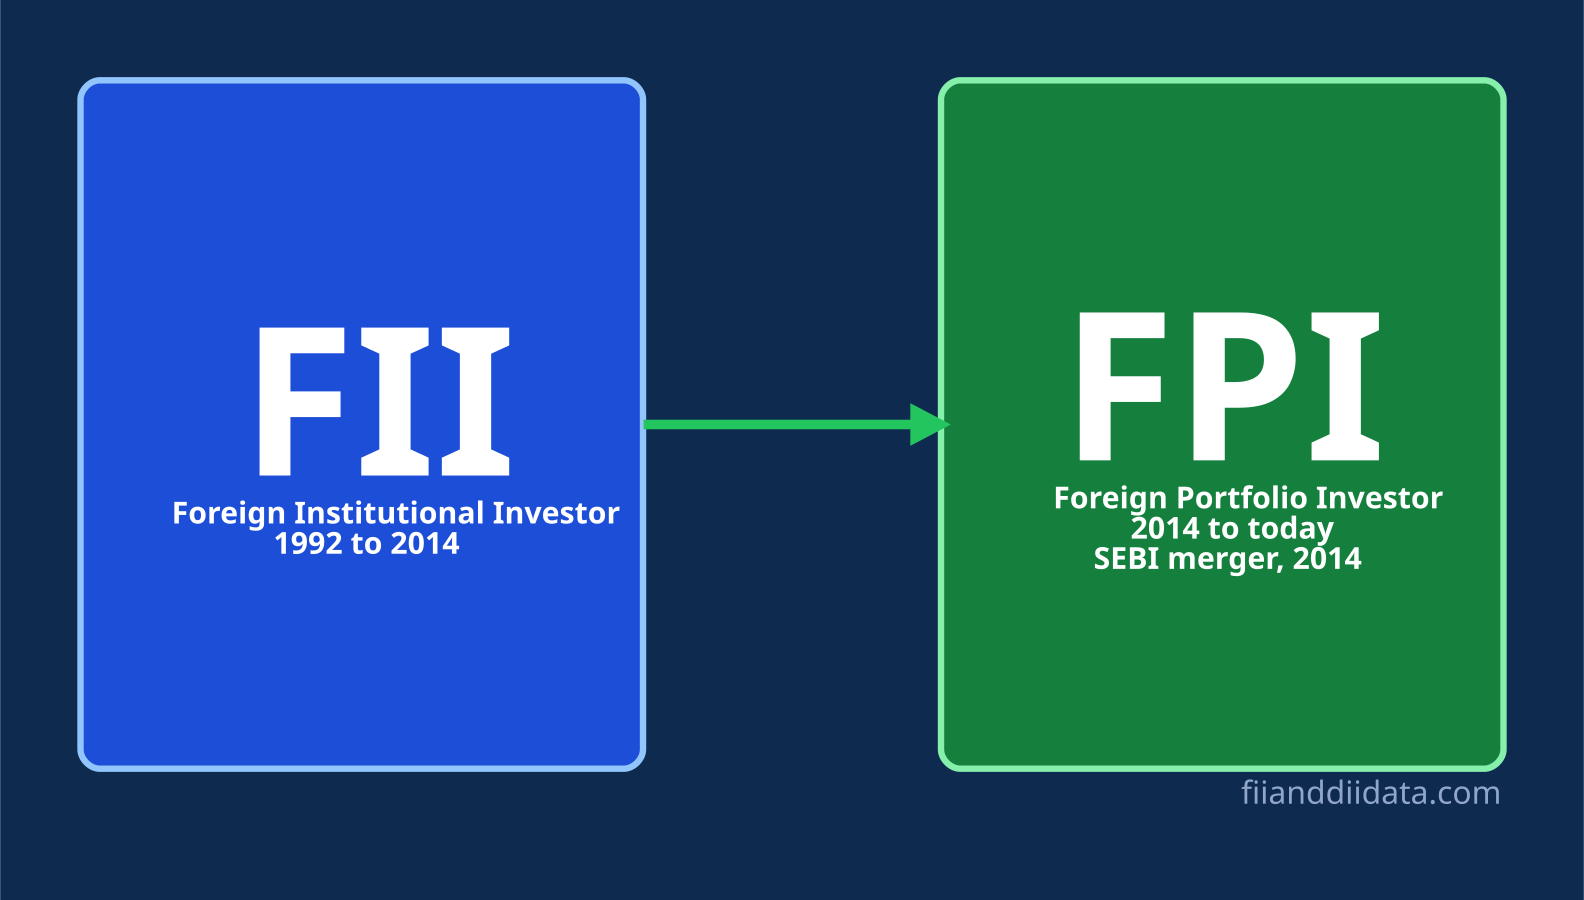
FII vs FPI is not a contest between two investor groups: both terms describe the same foreign money that moves Indian markets. FPI (Foreign Portfolio Investor) has been the legal term since SEBI merged FIIs into it in 2014, while traders still say FII out of habit. With FPIs holding ₹69.57 lakh crore of Indian assets on 31 March 2026, knowing how the label works helps you read every flow report correctly.
Key Takeaways
- FII and FPI refer to the same foreign investors; FPI is the official term since 2014.
- The SEBI (FPI) Regulations, 2019 sort FPIs into two risk-based categories.
- India had 12,199 registered FPIs with ₹69.57 lakh crore under custody on 31 March 2026.
- From 1 June 2026, low-risk FPIs can use SEBI’s SWAGAT-FI route with 10-year registration.
- NSE and NSDL figures differ in timing and coverage, so use each for the right job.
In this guide:
- What Is an FII?
- What Is an FPI?
- FII vs FPI: Key Differences
- FPI Categories in India
- What FPIs Can Buy and the Limits
- FII vs FPI Data: Latest Numbers
- How to Read FII and FPI Data
- Common Mistakes
- FAQs
- The Bottom Line
What Is an FII? The Old Term in FII vs FPI
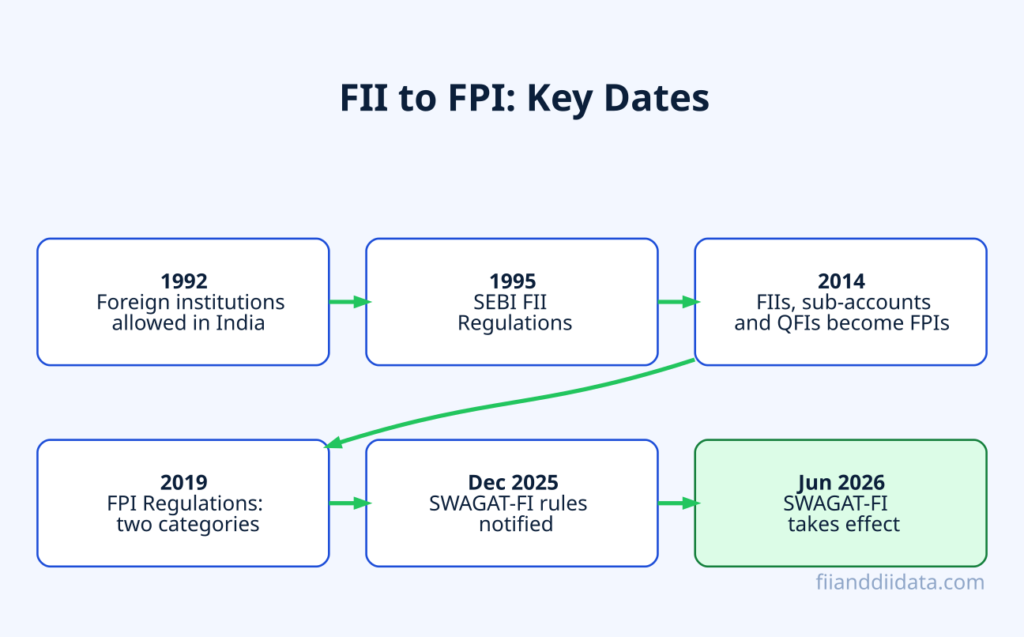
FII stands for Foreign Institutional Investor. India opened its stock market to foreign institutions in 1992, and SEBI regulated them under the SEBI (Foreign Institutional Investors) Regulations, 1995. Each institution registered directly with SEBI, and it could open separate sub-accounts for the funds it managed.
Typical FIIs were global asset managers, foreign pension funds, sovereign wealth funds, foreign banks and insurance companies. From 2012, a third group called Qualified Foreign Investors (QFIs) was added with its own rules. Three overlapping routes for the same type of money created paperwork and confusion, which set up the change that came next.
What Is an FPI? The Current Legal Term
FPI stands for Foreign Portfolio Investor. An FPI is a foreign entity that buys Indian shares, bonds, derivatives and other securities without taking control of the companies it invests in. A portfolio investor can sell quickly and move money out, which is why FPI flows are watched so closely.
SEBI created the FPI category through the SEBI (Foreign Portfolio Investors) Regulations, 2014, which merged FIIs, their sub-accounts and QFIs into one group. The 2014 rules were replaced by the SEBI (FPI) Regulations, 2019, which apply today. Instead of registering with SEBI directly, an FPI now registers through a Designated Depository Participant (DDP), usually a large custodian bank that checks its documents on SEBI’s behalf.
So the label changed, but the investors did not. The table below shows exactly what is different and what stays the same.
FII vs FPI: Key Differences in One Table
| Factor | FII (old system) | FPI (current system) |
|---|---|---|
| Period | 1992 to 2014 | 2014 to today |
| Main rules | SEBI (FII) Regulations, 1995 | SEBI (FPI) Regulations, 2019 |
| Who is covered | FIIs, sub-accounts and, separately, QFIs | One single category for all foreign portfolio investors |
| Registration | Directly with SEBI | Through a Designated Depository Participant |
| Risk classes | None | Category I and Category II |
| Where you see the term | TV, brokers, most data websites | SEBI, NSDL, CDSL, official filings |
| Market impact | Same investors, same money, same effect on Nifty and the rupee | |
Why Data Sites Still Say FII
NSE titles its daily report “FII/FPI & DII trading activity”, so both names sit side by side in the official source. Traders learned the word FII long before 2014 and kept using it. On FIIAndDIIData.com we use FII for daily exchange data and FPI when we quote NSDL figures, but the money is the same. If you are new to these reports, start with our guide on what FII and DII data means.
FII vs FPI vs FDI
FDI (Foreign Direct Investment) is the one term that really is different. An FDI investor takes a lasting stake, often with a say in management, such as a foreign parent owning an Indian subsidiary. The legal dividing line is 10%: if one foreign investor group owns 10% or more of a listed company’s paid-up equity, that holding is treated as FDI rather than portfolio investment. We work through this limit with numbers further down, after a look at how SEBI classifies FPIs.
FPI Categories in India Under SEBI Rules
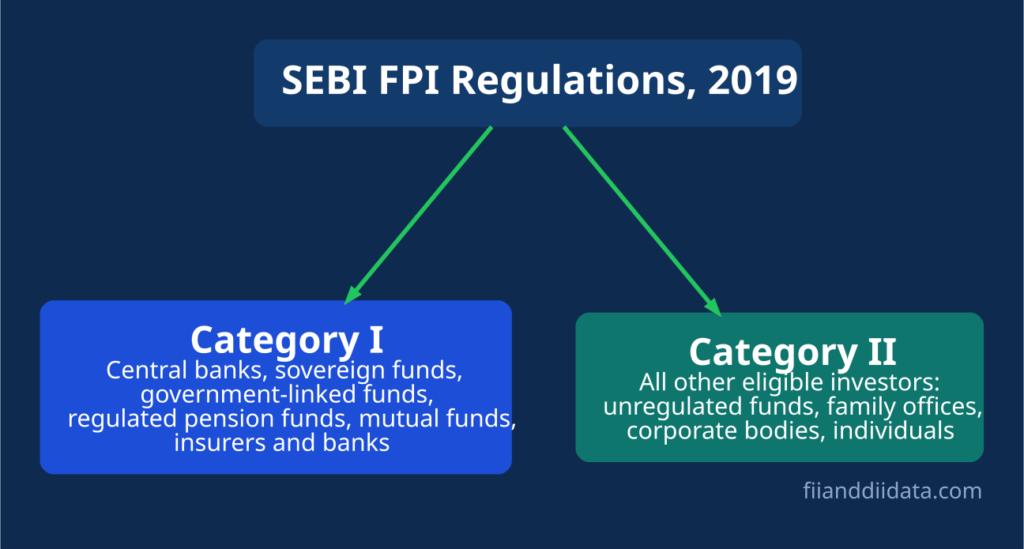
The 2014 rules had three FPI categories. The 2019 Regulations cut this to two, based on how risky and how well regulated the investor is. Lower-risk investors get lighter KYC and simpler paperwork.
| Category | Who qualifies | Typical examples |
|---|---|---|
| Category I | Governments, central banks, sovereign wealth funds, multilateral bodies, and regulated funds, insurers, pension funds and banks from FATF member countries | Sovereign funds, large global mutual funds and pension funds |
| Category II | All other eligible foreign investors | Unregulated funds, family offices, corporate bodies, individuals |
New for 2026: SWAGAT-FI for Trusted FPIs
SEBI has added a fast lane on top of the two categories. The SEBI (FPI) (Second Amendment) Regulations, 2025 were notified on 3 December 2025, and SEBI’s circular of 16 January 2026 set out the details of SWAGAT-FI (Single Window Automatic and Generalised Access for Trusted Foreign Investors). It applies from 1 June 2026.
Eligible investors include sovereign wealth funds, multilateral agencies, entities with at least 75% government ownership, regulated pension funds, regulated insurers and certain public retail funds. For them, registration and KYC review run for 10 years instead of the usual three-year renewal cycle. In plain terms, India is making it easier for patient, long-term foreign money to stay. That matters because these are the investors whose flows tend to be steadier, which brings us to what any FPI is actually allowed to buy.
What FPIs Can Buy and the Investment Limits
FPIs can invest in listed shares on NSE and BSE, index and stock futures and options, government securities, corporate bonds, mutual fund units, REITs and InvITs. Their positions in index futures show up every evening in the NSE participant wise open interest report.
- Single FPI limit: One FPI, together with its investor group, must hold less than 10% of a listed company’s paid-up equity.
- Aggregate limit: Since 1 April 2020, the default limit for all FPIs together in a company is the sectoral cap for foreign investment in that sector. Before that, the default was 24%.
- Sector caps: Some sectors have their own caps, for example 74% for private sector banks.
- Extra disclosure: In March 2025, SEBI raised the threshold for detailed ownership disclosure from ₹25,000 crore to ₹50,000 crore of equity assets under custody. The 50% single-group concentration test did not change.
Worked Example: When an FPI Holding Becomes FDI
Take a listed company with 100 crore shares. A foreign fund group owns 9.5 crore shares, which is 9.5% of equity, so it is a portfolio investment. If the group buys another 0.6 crore shares, it holds 10.1 crore shares or 10.1%. It has now crossed the 10% line, so it must either sell down below 10% within the allowed time or have the holding reclassified as FDI under the FDI rules. This is why large FPIs watch their stake levels closely before adding to a position.
FII vs FPI Data: The Latest Numbers for 2026
The size of the FPI base explains why their selling moves the market. Here are the most recent official and reported figures.
| Measure | Value | As of |
|---|---|---|
| Registered FPIs | 12,199 | 31 March 2026 |
| FPI assets under custody | ₹69,57,108 crore | 31 March 2026 |
| FPI assets under custody a year earlier | ₹73,76,495 crore (the 2026 figure is 5.7% lower) | 31 March 2025 |
| Net FPI flow, FY 2025-26 | Outflow of ₹1,52,692 crore, the largest annual outflow on record | April 2025 to March 2026 |
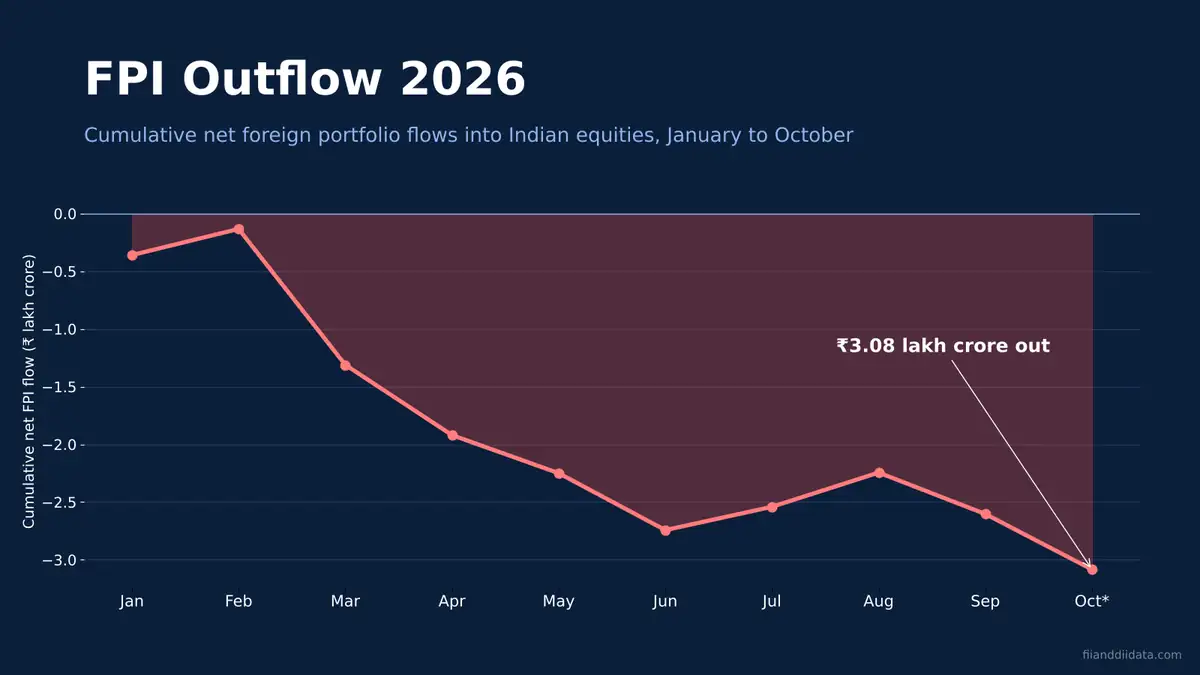
| Net FPI outflow from equities, 2026 so far | ₹2.69 lakh crore | Reported 4 October 2026 |
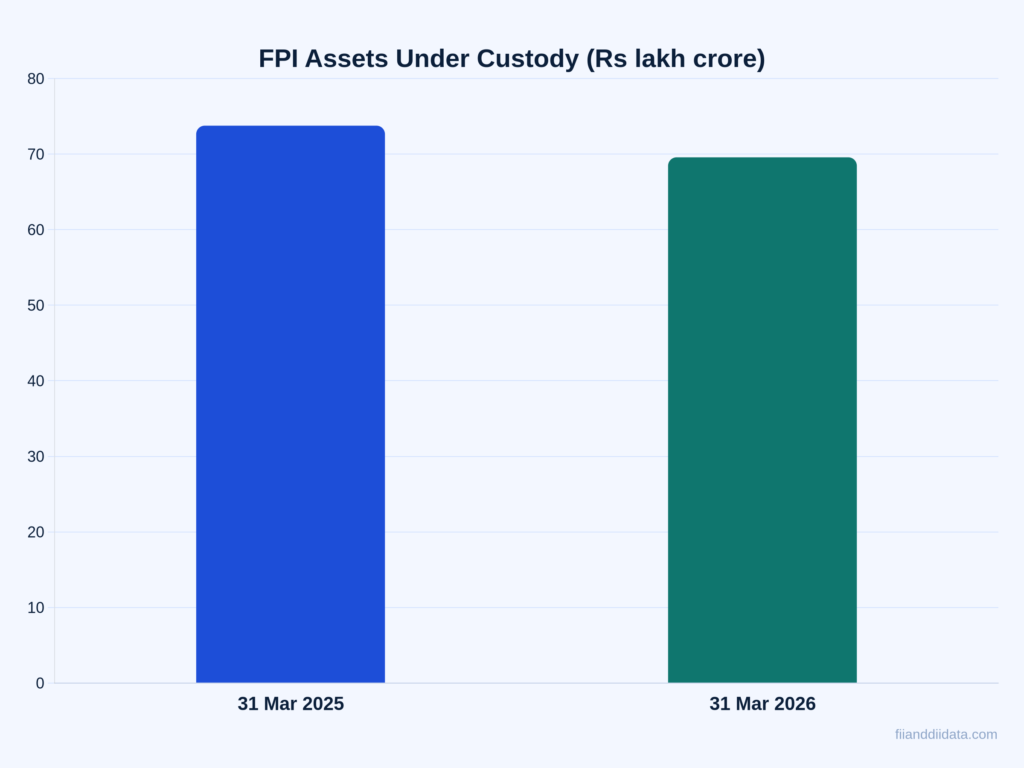
The fall in custody assets came from two forces at once: lower share prices and steady net selling. You can see how that selling built up month by month in our FPI outflow 2026 data, and how domestic funds absorbed it in our difference between FII and DII guide. Numbers like these only help if you know which report they came from, so the next section explains how to read them.
How to Read FII and FPI Data Correctly
| Report | What it shows | When it comes out |
|---|---|---|
| NSE provisional cash data | FII/FPI and DII gross buy, gross sell and net value in the cash market | Trading days, around 6 PM IST |
| NSE participant wise open interest | Long and short F&O positions of FII, DII, Pro and Client | Trading days, in the evening |
| NSDL FPI data | Final FPI flows including IPO and other primary market buying, by day, month and year | Next working day |
For example, on 23 October 2026 NSE provisional data showed FIIs as net buyers of ₹888 crore in the cash market. That is a one-day exchange figure. NSDL’s number for the same day can differ because it settles a day later and includes primary market money such as IPO allotments.
A Five-Step FII vs FPI Data Checklist
- Check the source label: NSE (exchange, provisional) or NSDL (depository, final).
- Check the date and whether it is a trade date or a settlement date.
- Check whether primary market (IPO) money is included.
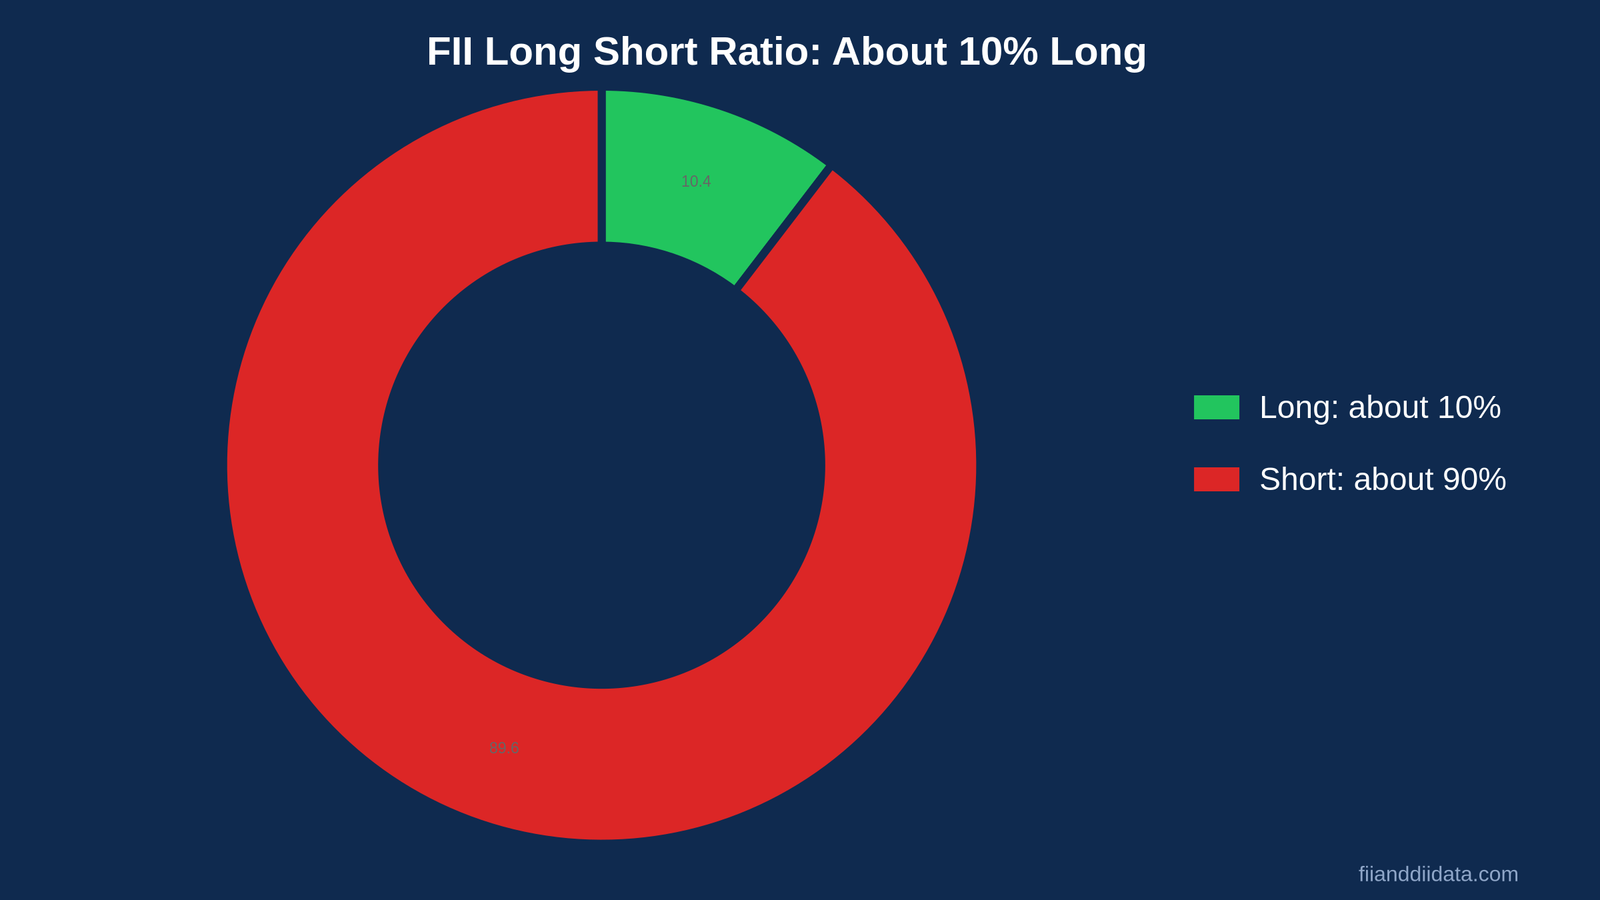
- Read cash flows together with derivatives positions, such as the FII long short ratio.
- Compare with DII flows on the same day before drawing a conclusion.
We publish the daily FII and FPI cash market data every trading evening and the monthly FII DII data for longer trends. Even with the right report open, a few mistakes come up again and again.
Common Mistakes When Reading FII vs FPI Numbers
- Adding FII and FPI figures together: They are the same investors, so adding an NSE “FII” number to an NSDL “FPI” number counts the same money twice.
- Treating FPI and FDI as the same: FDI is long-term, controlling money and moves slowly. FPI money can leave in days.
- Expecting NSE and NSDL to match: Different timing and IPO coverage mean small gaps are normal.
- Reading one day as a trend: A single buying day, like 23 October 2026, says little after months of net selling.
- Ignoring derivatives: FPIs can sell shares and hedge with index futures at the same time, so cash data alone gives half the picture.
Avoid these and the FII vs FPI naming question stops mattering. The questions below cover what readers ask us most often.
Frequently Asked Questions
FII vs FPI: is there any real difference?
There is no practical difference in the investors. FPI (Foreign Portfolio Investor) is the legal term SEBI has used since 2014, when it merged FIIs, their sub-accounts and QFIs into one category. FII is the older name that traders and data sites still use.
Is FII still a valid category in India?
No. FII is no longer a separate legal category. Investors that were FIIs now register as FPIs under the SEBI (FPI) Regulations, 2019, though NSE still labels its daily report FII/FPI.
How many FPI categories are there in India?
There are two. Category I covers governments, central banks, sovereign funds and regulated entities from FATF member countries. Category II covers all other eligible foreign investors. From 1 June 2026, trusted low-risk investors can also use the SWAGAT-FI route.
What is the difference between FPI and FDI?
FPI is a portfolio investment in securities that can be sold quickly. FDI is a long-term stake, often with management influence. A holding of 10% or more of a listed company by one foreign investor group is treated as FDI.
Who regulates FPIs in India?
SEBI regulates FPIs under the SEBI (FPI) Regulations, 2019. Registration is handled by Designated Depository Participants, and RBI and government rules set the overall foreign investment limits by sector.
The Bottom Line
FII and FPI are two names for one group of foreign investors. FPI is the legal term under SEBI’s 2019 rules, with two risk categories and, from June 2026, a SWAGAT-FI fast lane for trusted long-term funds. FII survives as everyday market language and in NSE’s report title.
What changes your trading is not the label but the flow: how much foreign money is coming in or going out, and how it lines up with DII buying and derivatives positions. As a next step, open today’s FII and DII figures after 6 PM IST and run them through the five-step checklist above. You can find more explainers in our FII DII guides.
Sources: SEBI publication, Chapter 6: Foreign Portfolio Investors (August 2026); Business Standard, 4 October 2026; Business Standard, 24 March 2025; Outlook Money on SWAGAT-FI, 17 January 2026; NSE India provisional FII/DII data (23 October 2026); SEBI (FPI) Regulations, 2019.
Disclaimer: This article is for educational purposes only and is not investment advice. Please consult a SEBI-registered advisor before making investment decisions.